

Kapital ist gefährdet. Sie können Ihr gesamtes Investment verlieren. Die vollständigen Risikohinweise finden Sie hier.
British semiconductor architecture designer Arm Holdings’ (ticker: ARM) earnings report for the second quarter (Q2) of its Fiscal Year (FY) 2026 – released on the 6th of November this year – accomplished a rare feat for AI-relevant stocks (despite record results) in this earnings season: a modestly positive market reaction.
A couple of factors contributed to this positive uptick in investor sentiment.
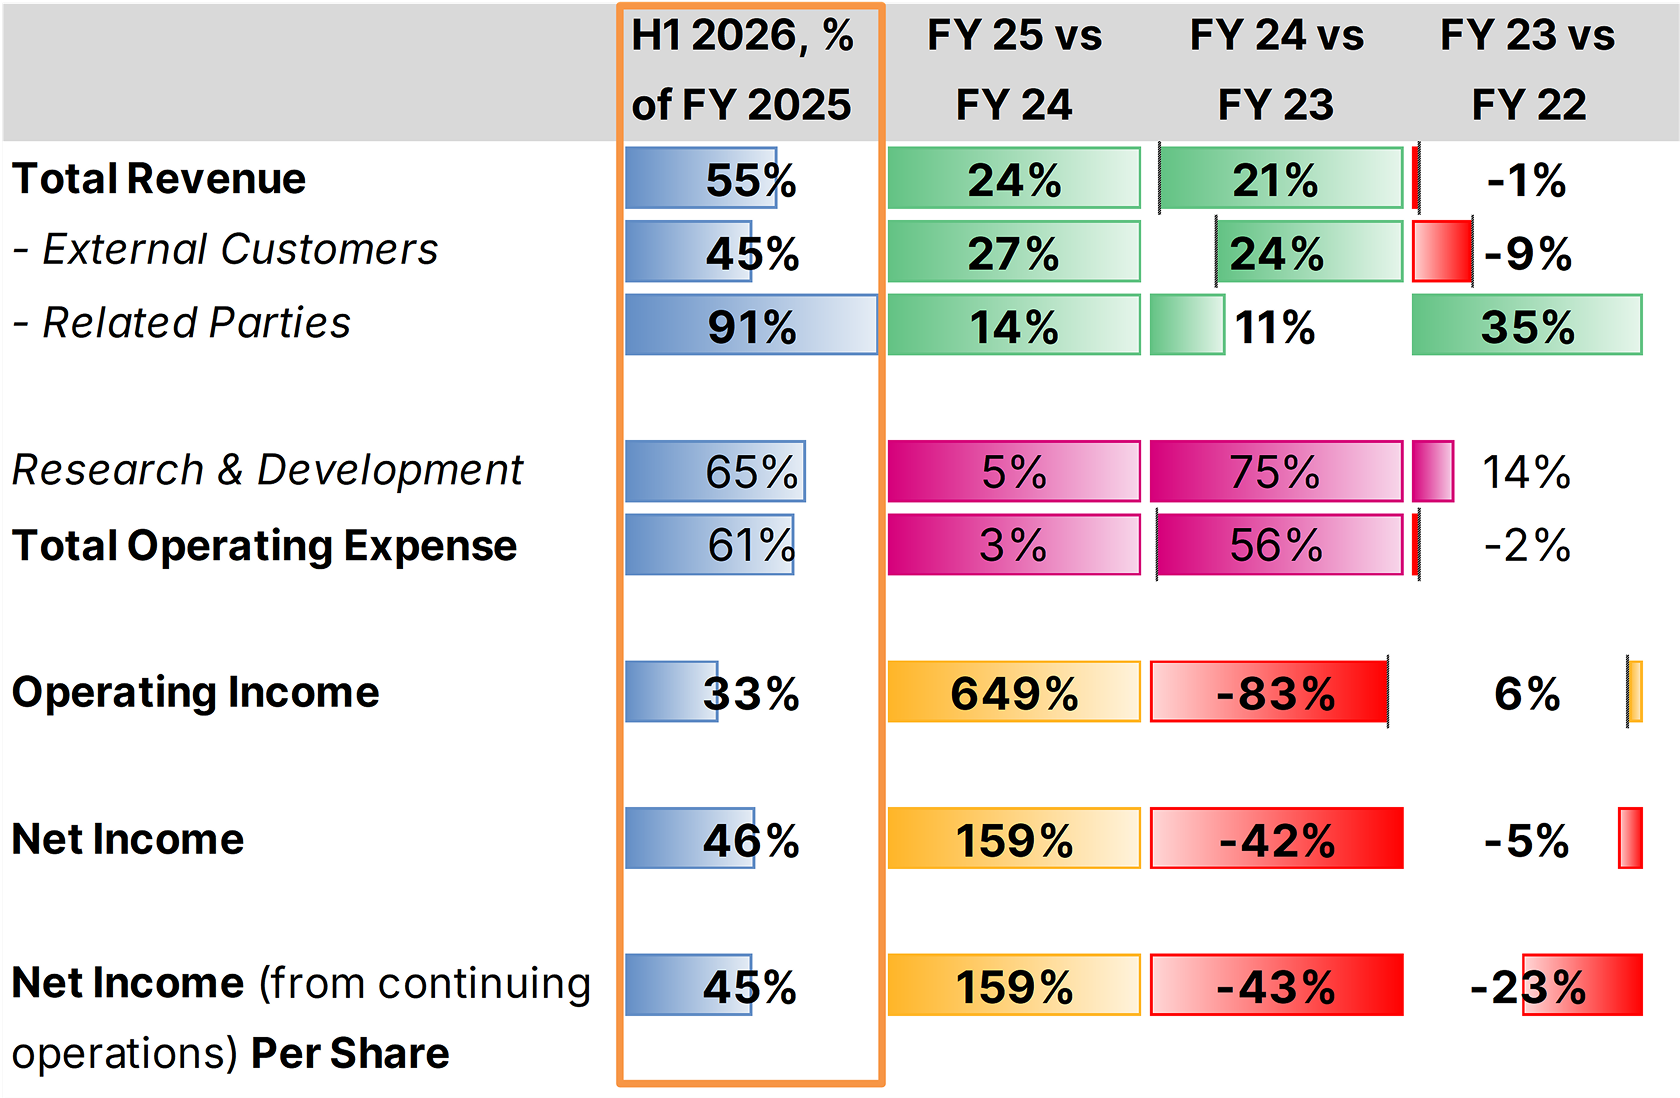
Trend AnalysisIf trends exhibited in the first half (H1) in Arm’s current fiscal year were to hold true for the rest of the year, revenue growth can be expected to be 10% – as opposed to the 4% implied by the company’s Q1 results.
Source: Company Information; Leverage Shares analysis
With trends in operating expense holding steady from Q1, both operating and net income see a substantial trend improvement towards greater contribution to net income. While Q1 had the trend established at running at a 36% shortfall relative to the previous FY’s massive performance, H1 sees the gap narrowing to a mere 10%.
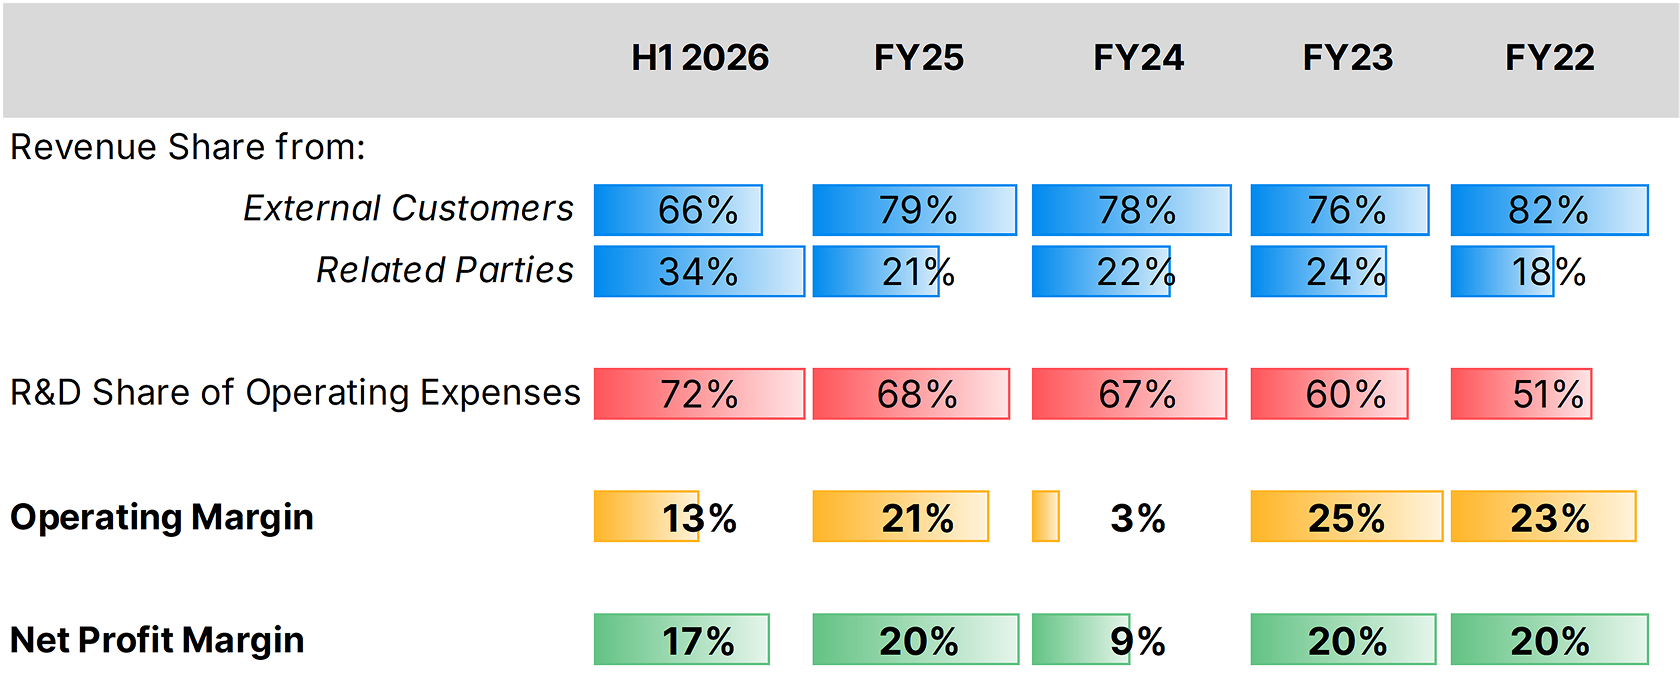
While the revenue trend from “External Customers” – constituting companies like Apple, Nvidia, Qualcomm, Samsung Electronics, et al – who license the architecture developed by Arm to design chips – remains in line with trends seen in Q1 (i.e. around a net 10% drop from the previous FY), an uptick in revenues from “Related Parties” – trending to be a near-doubling from the previous FY’s – helped raise revenue and net income trends.
Source: Company Information; Leverage Shares analysis
“Related Parties” predominantly defines Arm’s relationship with SoftBank, which licenses its technology to Chinese clients. In its FY 2025 report, the company stated that revenues from China accounted for 18% of revenue. In response to a query during the Q2 earnings call which posited a rise of revenue from China to 22%, Arm’s CFO Jason E. Child replied that licensing was the main driver for the company in the recent quarter and that one of its largest licensing deals has originated from China. He also added that royalty payments from China for the usage of its architecture is also growing strong.
The “Circular AI Deal Machine” and Forward OutlookOne potential standout favouring Arm among AI-relevant stocks has been its relative non-exposure to the “Circular AI Deal Machine”. As the recent article about Meta and Google1 as well as AMD2 elaborated, the “Circular AI Deal Machine” has chipmakers, cloud providers and AI companies enmeshed in a cycle of investments into each other followed by the provision of products and services. With each “deal”, stock valuations rose in the midst of the AI Hype. Given that AI hasn’t proven to be as monetizable relative to costs, some of this AI Hype is unspooling.
Arm has maintained its business model of simply licensing its architecture out to prominent players. One single prominent sign of a “deal” has been with Meta: a “strategic partnership” that will see Meta utilizing Arm’s Neoverse-based data center platforms to further optimize its ranking and recommendation systems while delivering optimized software components for use by the global open-source community. This partnership doesn’t yet have a disclosed “quid pro quo” typical of the “Deal Machine”. The absence of complexity in Arm’s business relationships might have helped reassure investors of relative stability.
Another factor might have been the announcement of a U.S.-China “framework” in the course of President Trump’s tariff war with the world. China’s access to advanced technology developed in the West has been a long-standing contention with bipartisan support in the U.S. legislature and, as the financial trends indicate, Arm has a substantial exposure in China which could be targeted with greater scrutiny and restrictions. The “framework” essentially belays the risk to some extent. However, the “framework” isn’t a resolution of tensions; it is merely a pause.
While China and a decline in the AI Hype might be long-term factors that will determine demand for Arm’s offering, Arm carrying on with “business as usual” without restrictions or circuitous deals might have resonated positively with the investing public in this earnings season. However, it bears noting that the China issue is likely to remain an ever-present matter of concern.
Professional investors in Europe may consider the +3x Long ARM ETP (ARM3) for magnified exposure during upsides of the stock’s trajectory.
Footnotes:
"Meta and Google: Revenue Growth Concerns, Costly AI", Leverage Shares, 3 November 2025
"Here's Why AMD Didn’t Rise After Q3 Earnings Results", Leverage Shares, 7 November 2025
Kapital ist gefährdet. Sie können Ihr gesamtes Investment verlieren. Die vollständigen Risikohinweise finden Sie hier.
 Market Insights