


Capitale a rischio. Potreste perdere tutto il vostro investimento. Consultate l'avvertenza completa sui rischi qui.
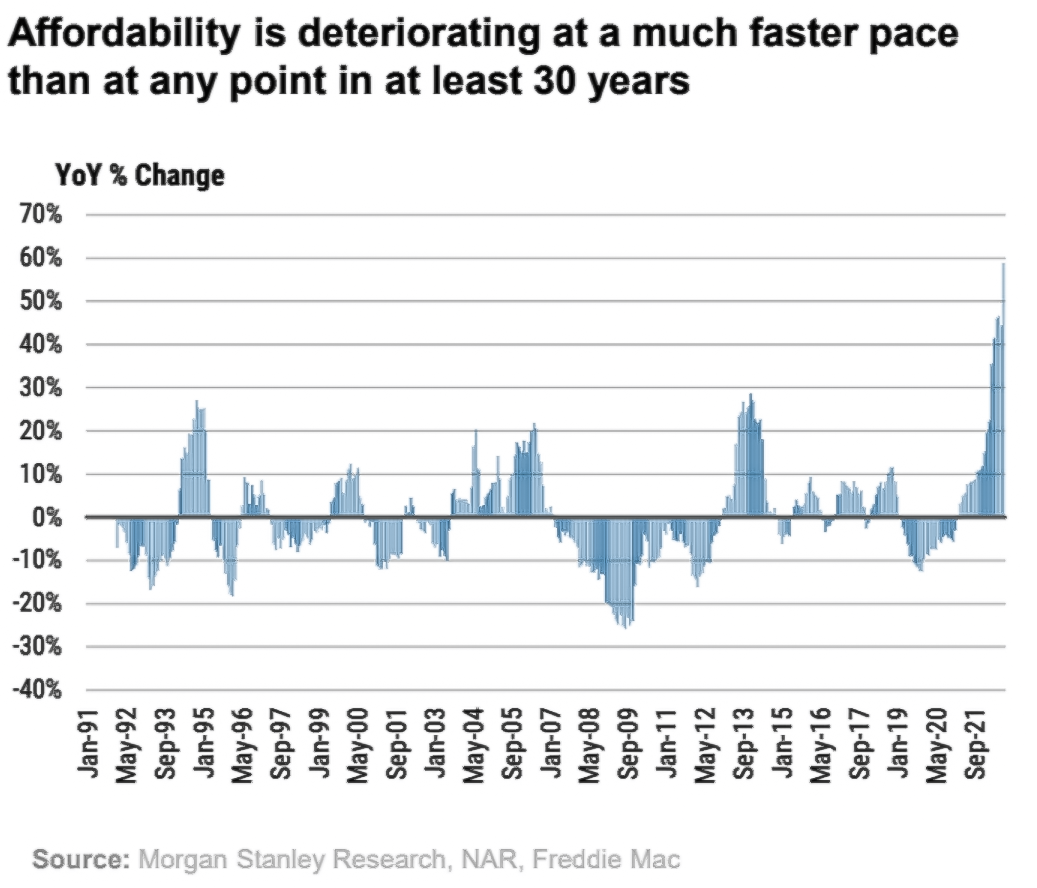
The US housing market is facing enormous headwinds: as of the end of October, the affordability measured in Year-on-Year (YoY) terms, has deteriorated by almost 60%, which was a faster change than in the past 30 years:
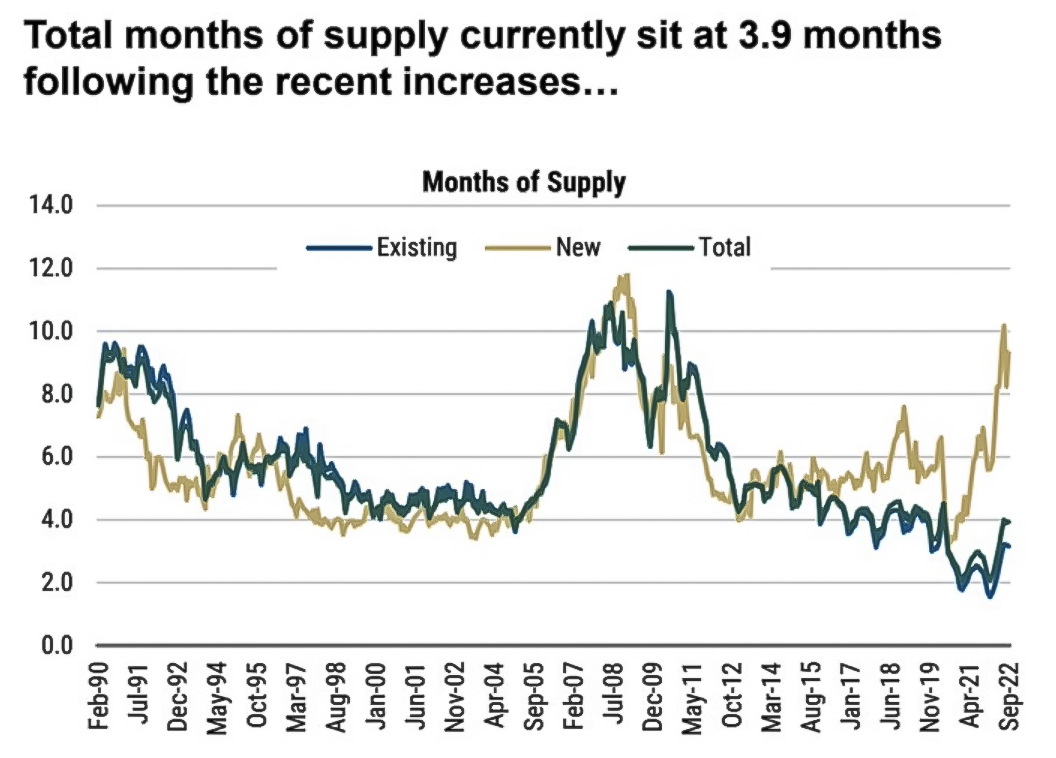
Nearly 10 months' worth of supply of new homes are lying in inventory while the listing of existing homes also faced a sharp spike in time across Q3.
Sales of existing homes, that tend to lie in relatively established in-demand areas, have been falling harder than it ever has in the last 30 years.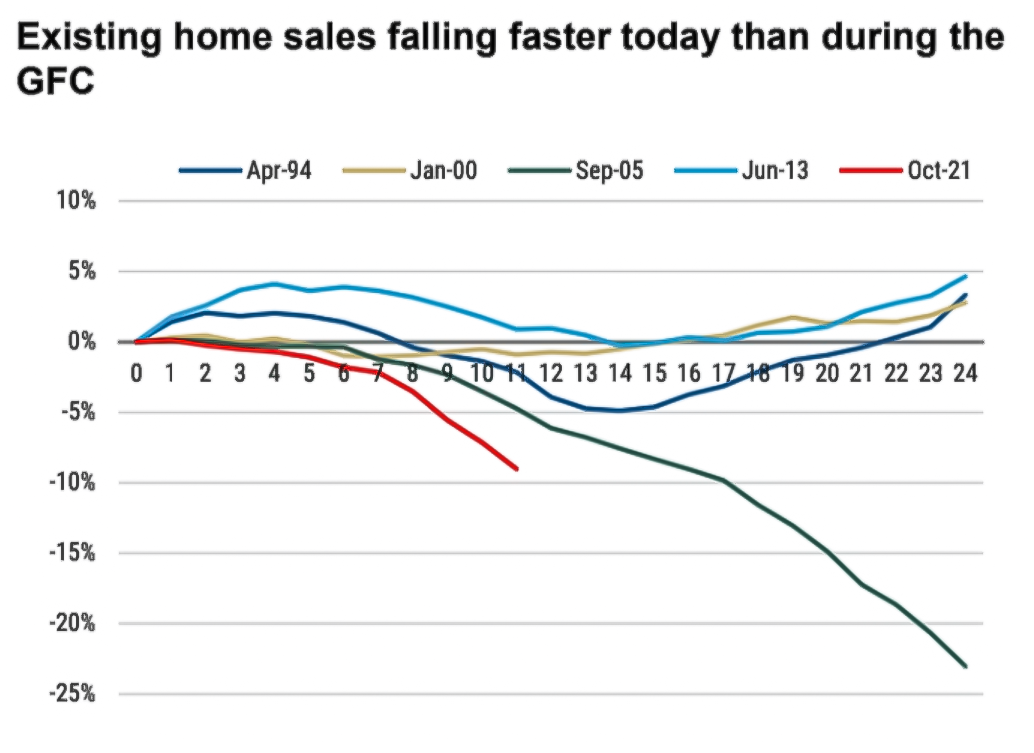
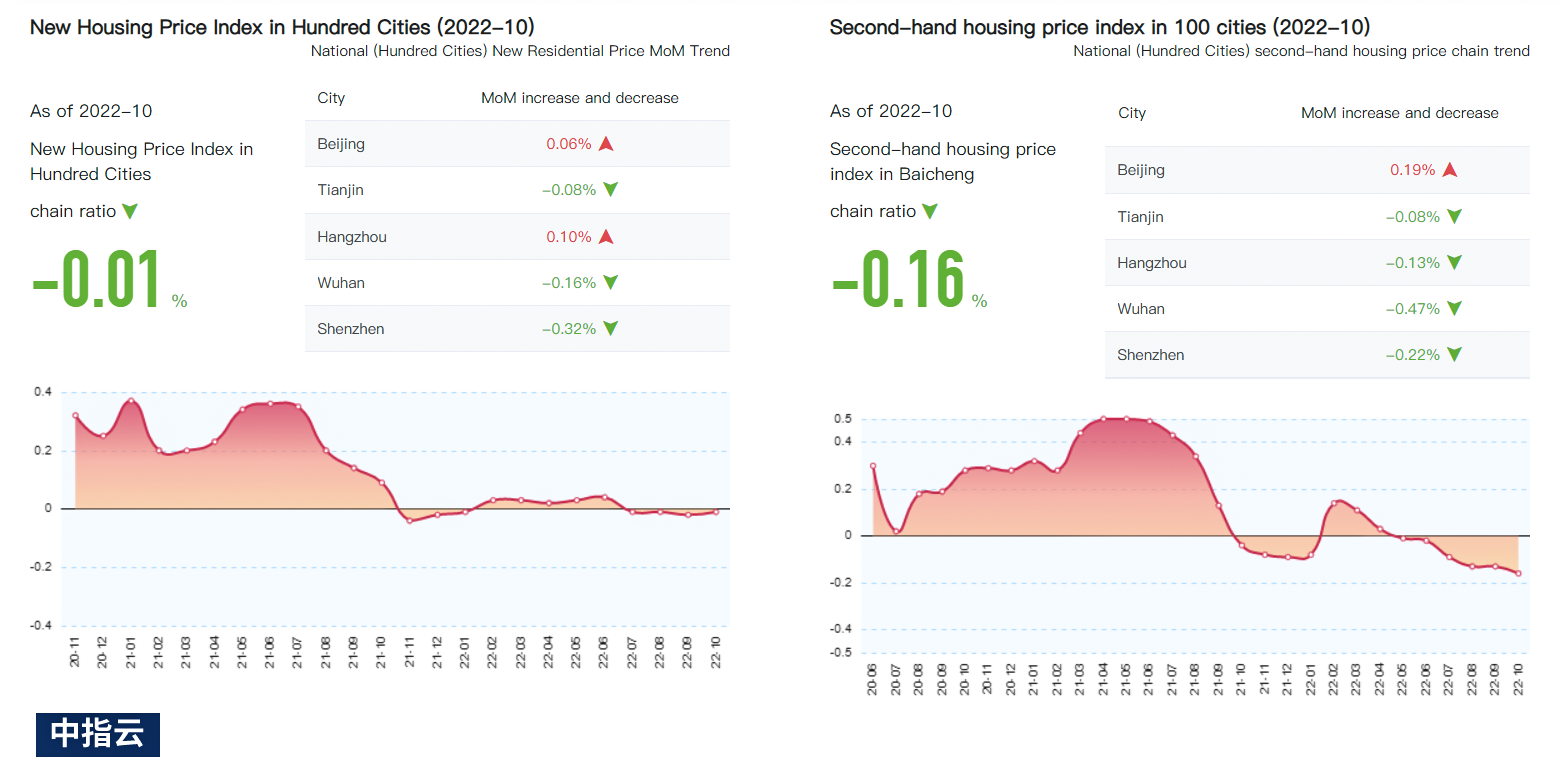
Meanwhile in China, it has been estimated that sales of new homes as of end of October have flatlined while the sales of existing homes have been falling faster and faster in the Year to Date (YTD):
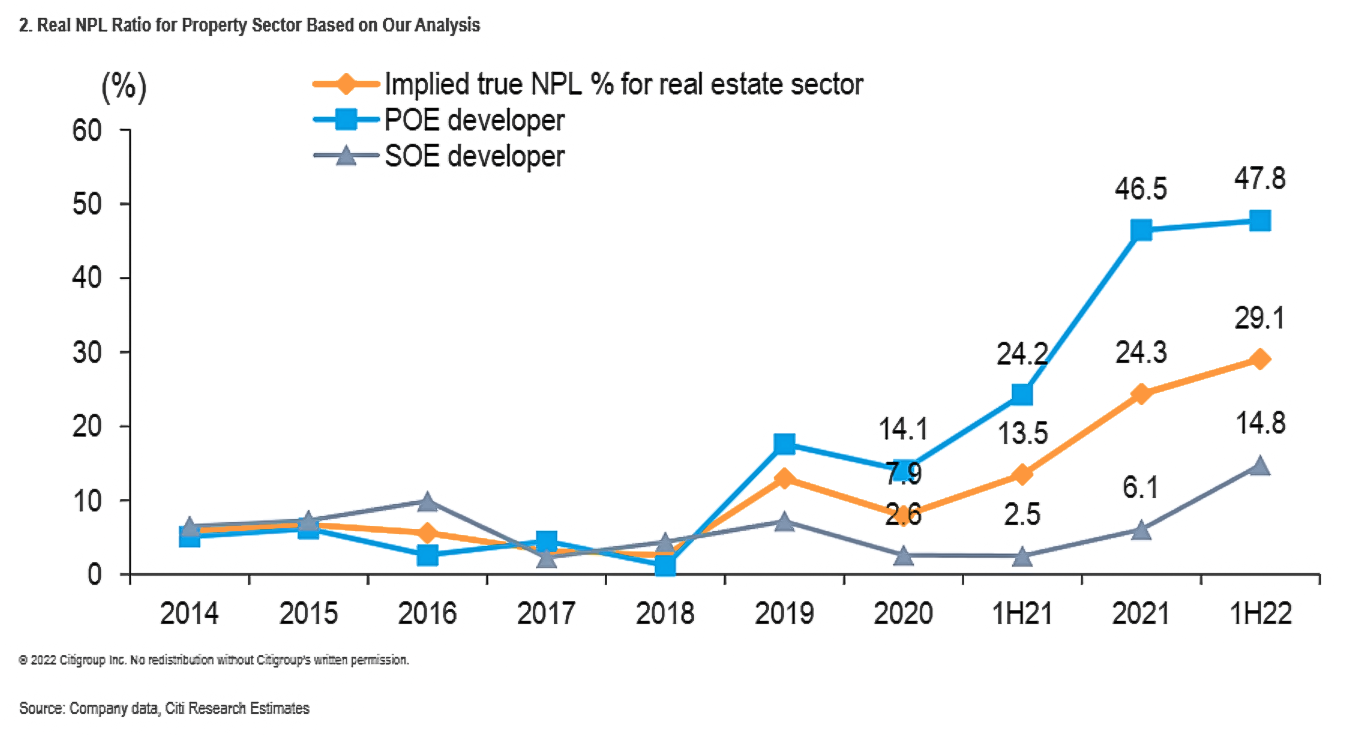
Earlier in the year, Citi's researchers had already indicated that non-performing loans in China's real estate market have been ratcheting, with privately-owned enterprises (POEs) bearing the brunt of this downward pressure.
This has grave consequences for the Real Estate Investment Trust (REIT) market, which typically tends to be a source for capital flight during market downturns. In this case, be it Chinese or US REITs, it is an open question if this is a better market than equities in the current environment.
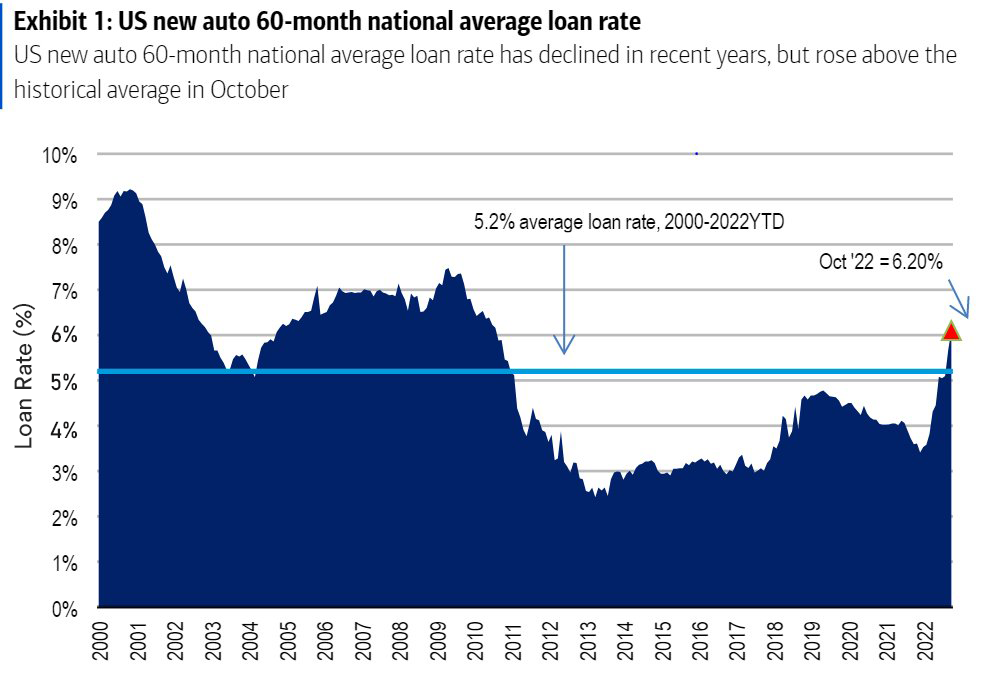
With regard to auto loans in the U.S., loans for new automobiles are at 5-year highs at a time when car sales have been in a steady downward spiral for a little over 10 years now.
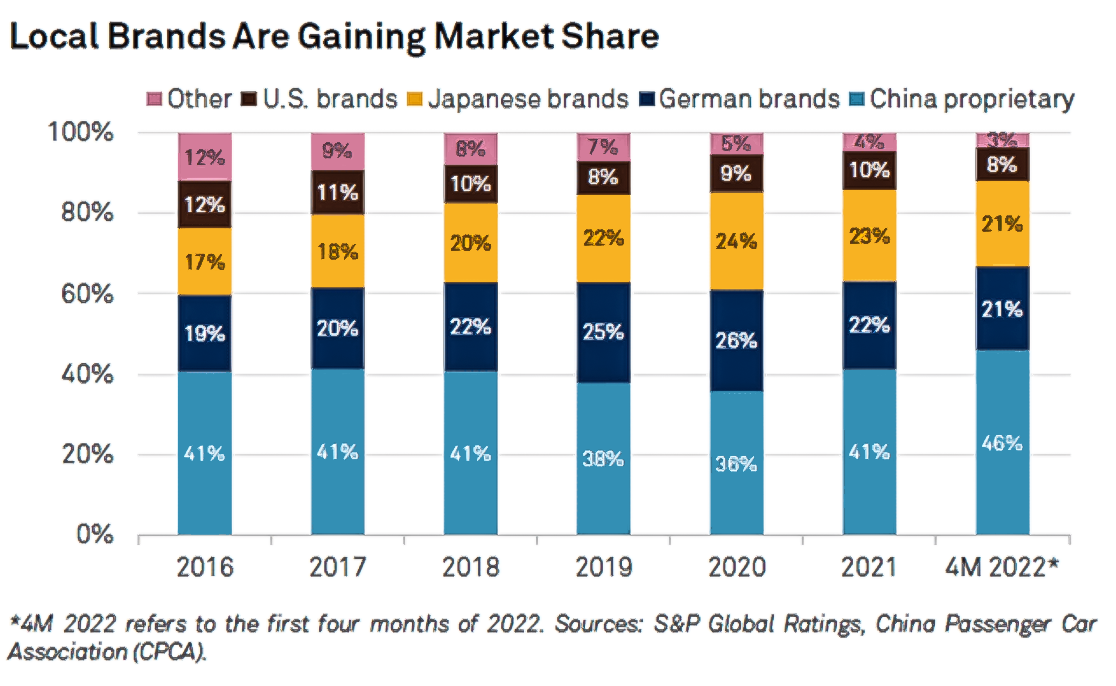
Similar figures don't exist in China but it has been noted that, by the middle of Q2 this year, sales of Chinese brands - which tend to be a little cheaper and attract subsidies than more expensive foreign brands - have seen a substantial increase in market share.
Now, Fitch Ratings reports that as of 2020, roughly about 50% of buyers obtained vehicle financing for their purchases. Early in 2021, the Chinese government launched a support initiative to increase credit support to boost the penetration rate and growth of auto financing. This involved asking auto captive loan financing business to lower their down-payment requirements, interest rates and tenors, which the agency warns could have an adverse effect these providers' asset quality and capitalization. Immediately after this announcement, there was some deterioration in the managed portfolios of Asset-Backed Securities (ABS) issuers specializing in auto loans, which was characterized by higher Loan-to-Value (LTV) Ratios and longer tenors on the loans. Given the argument that the growth in sales of cheaper Chinese brands have increased, it could also be argued that Chinese spending on automobiles have also deteriorated and being propped up by cheap loans.
The Chinese government's boost on spending is also reflected in the steady fall of the bank loan prime rate, which saw a precipitous fall in early 2020 and have continued to fall since.
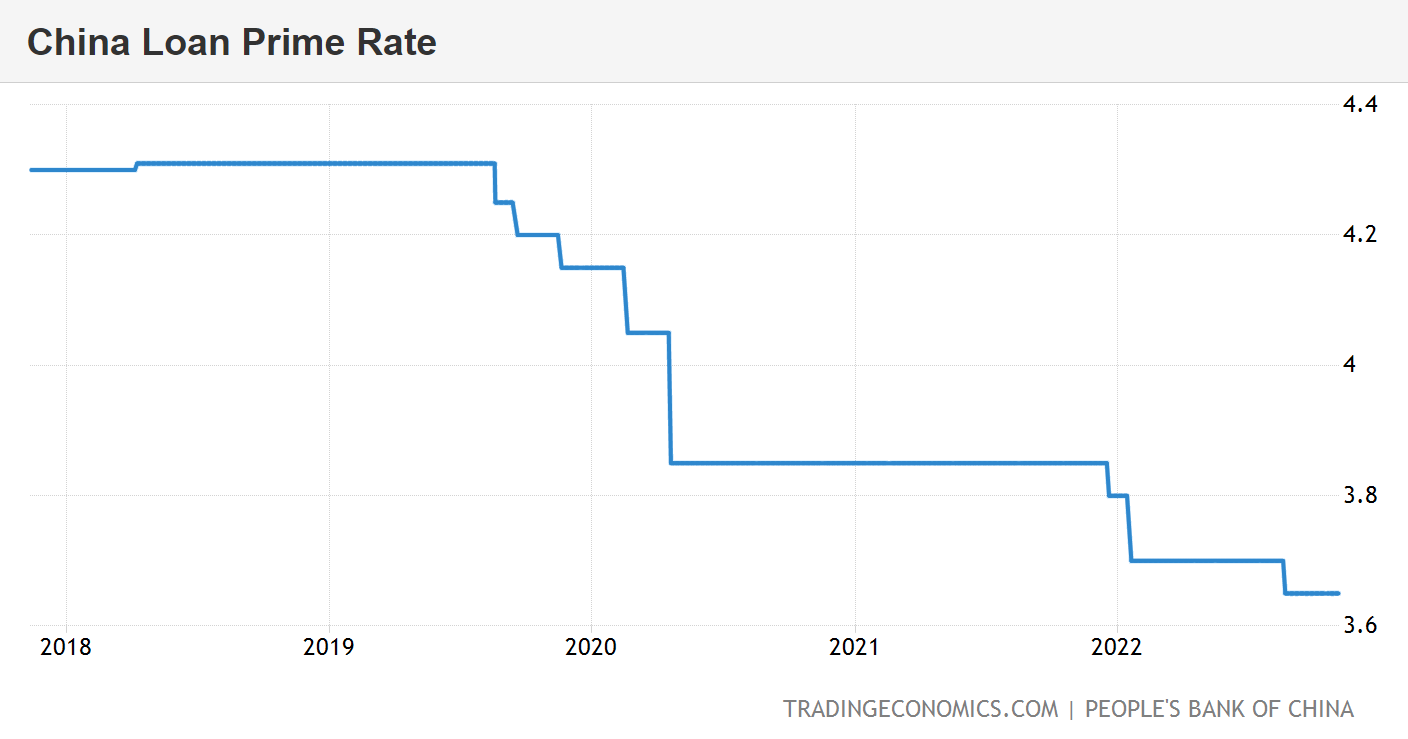 This implies that spending has been getting tighter for quite some time now.
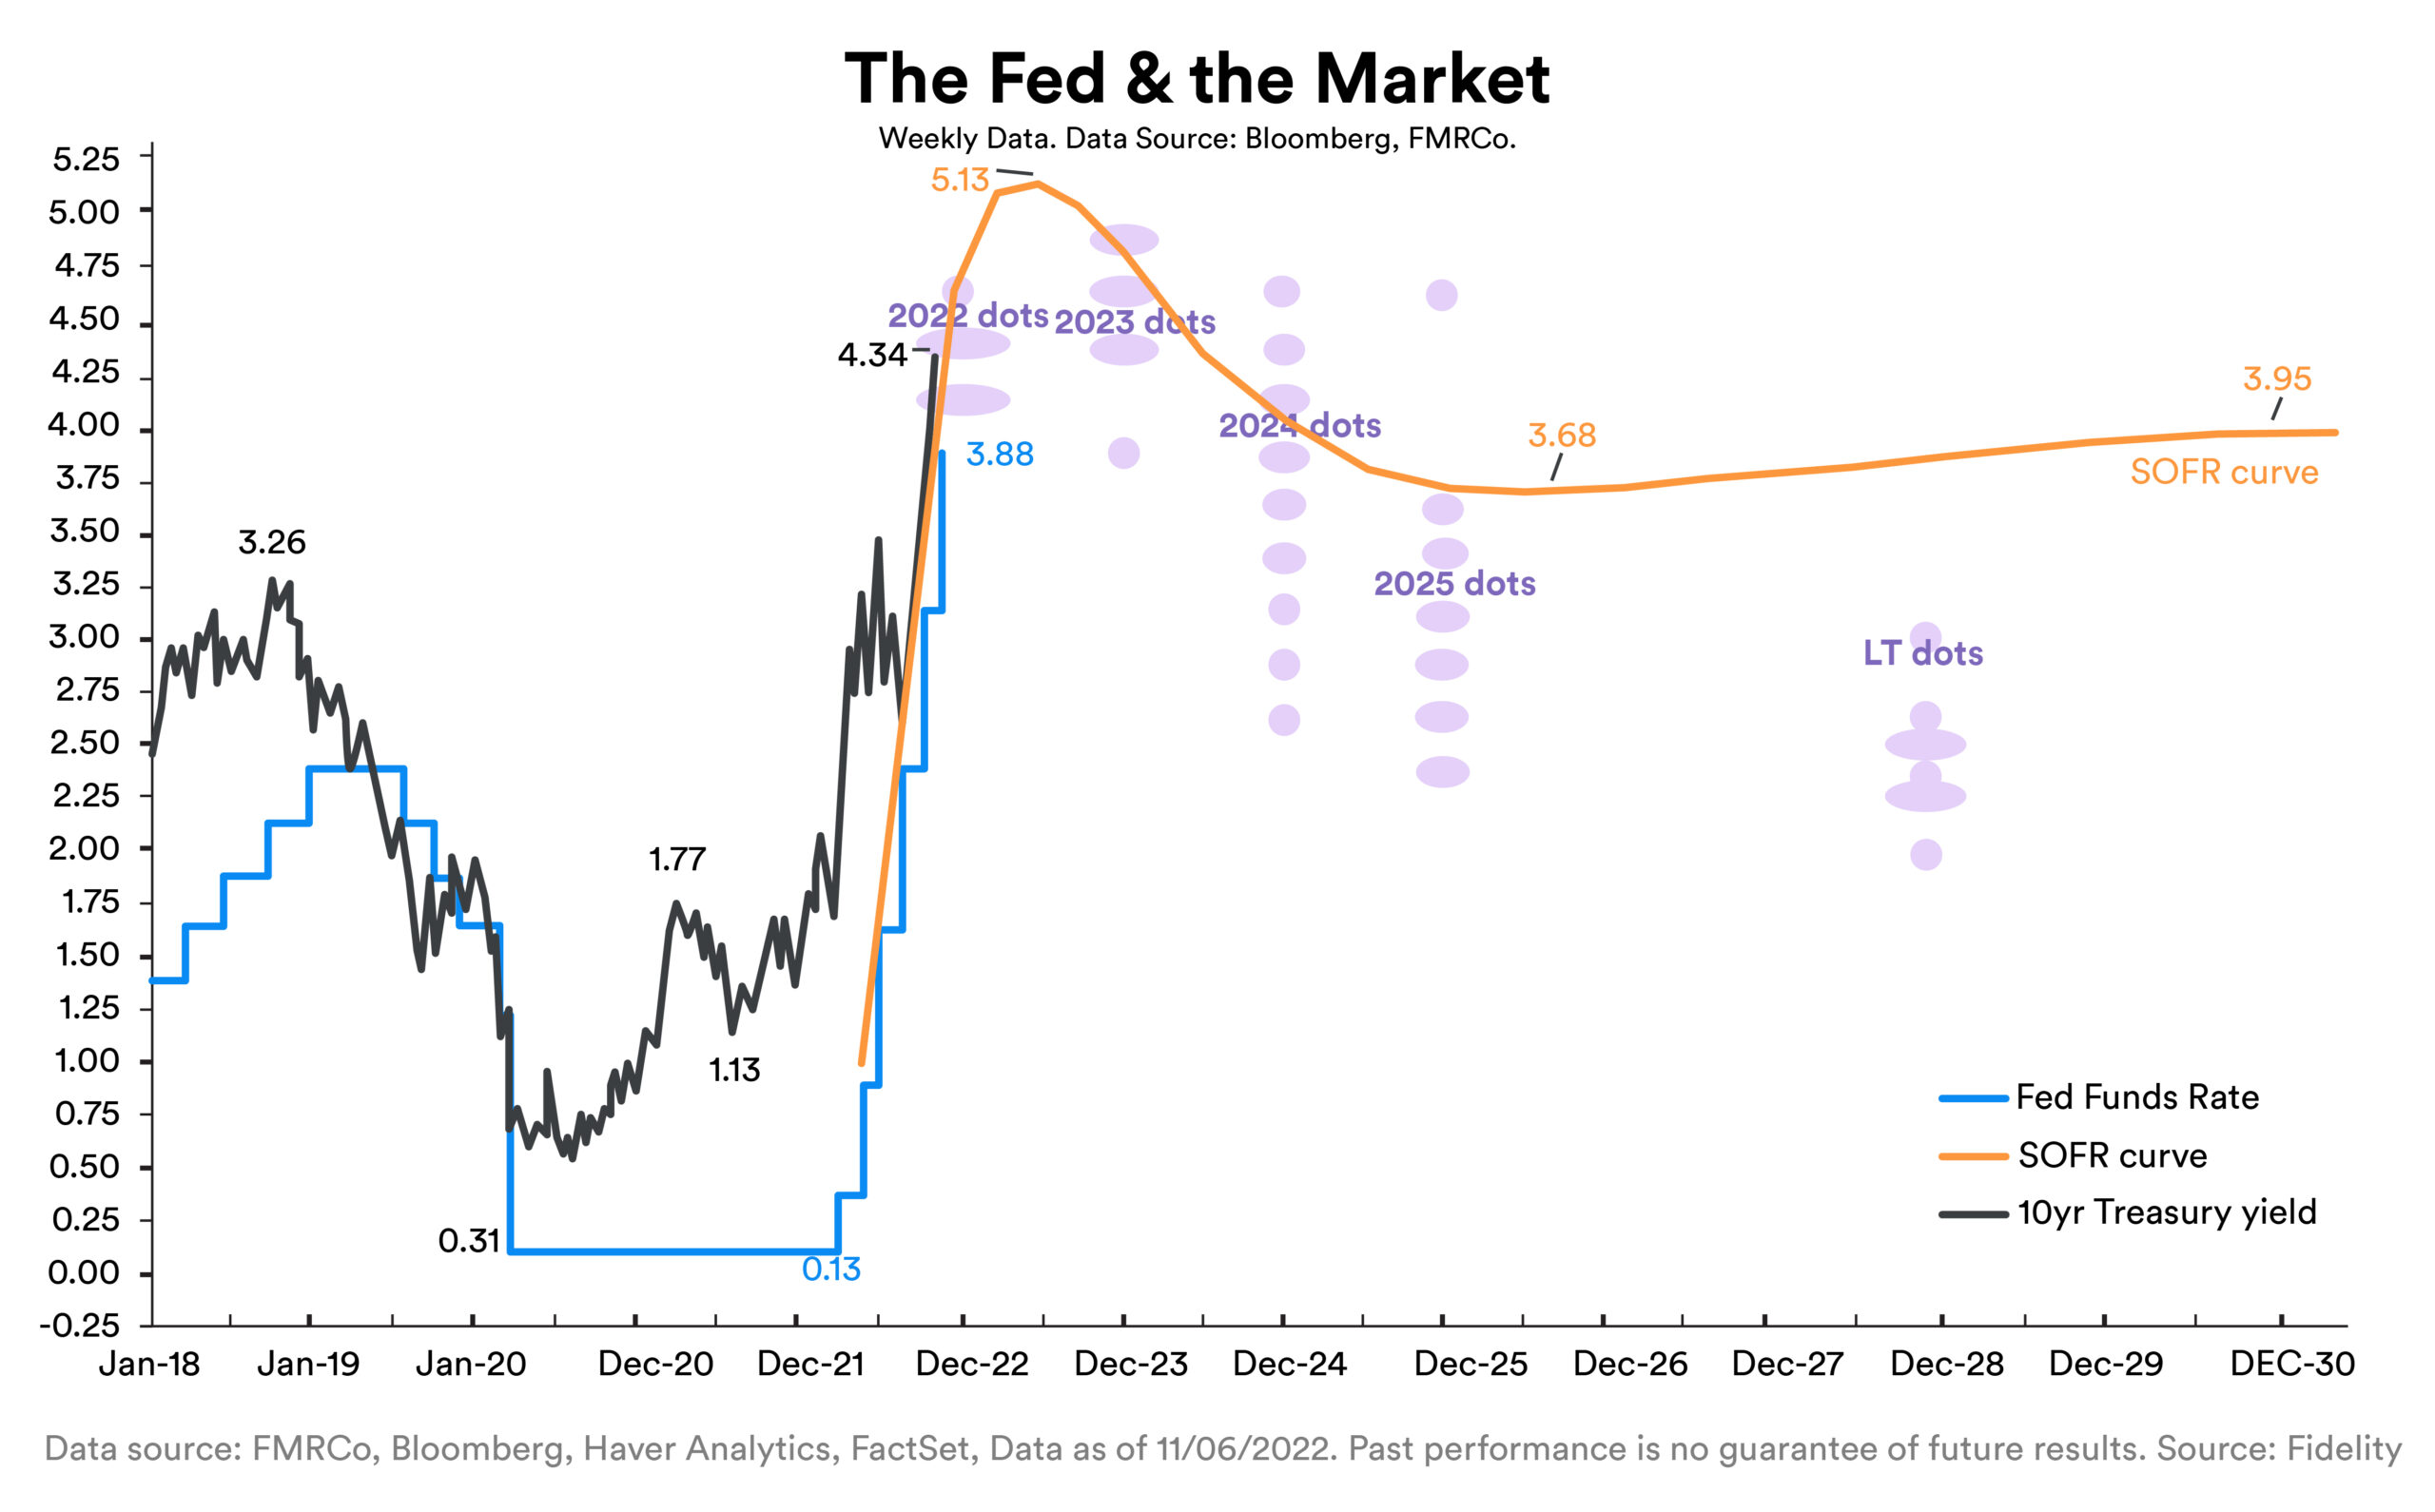
Meanwhile in the US, consensus expectation from institutional market players shows that Fed rate hikes will continue, implying that money will continue to depart from equity markets in the near future.
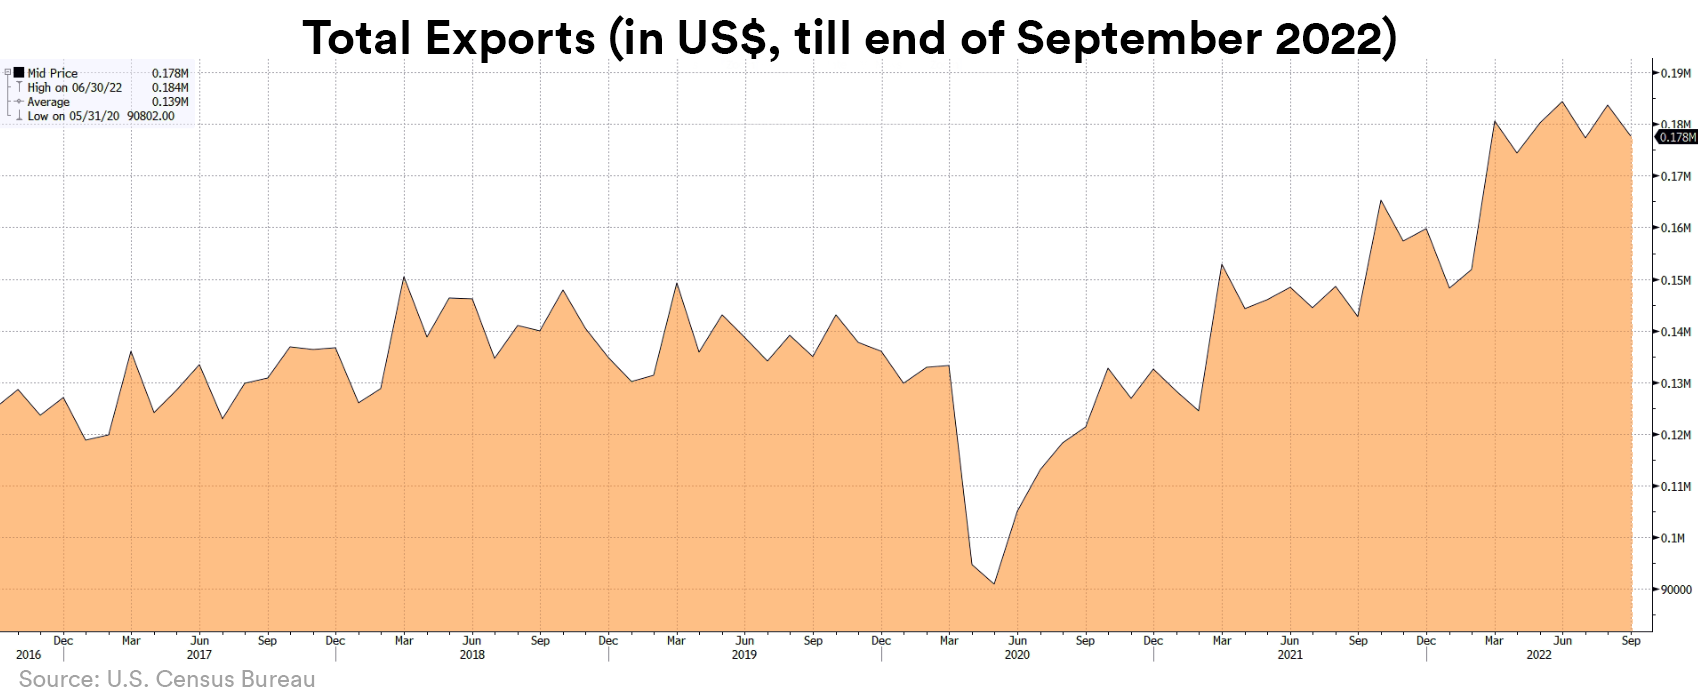
Next, lets consider exports. The US is the world's largest consumer of products virtually across the board while China is the world's largest producer across the board. Both countries are among each other's list of top trading partners. Overall exports from the US, largely helped by rising gas prices and increased exports to the European Union, have helped boost the value of exports all the way till the end of September.
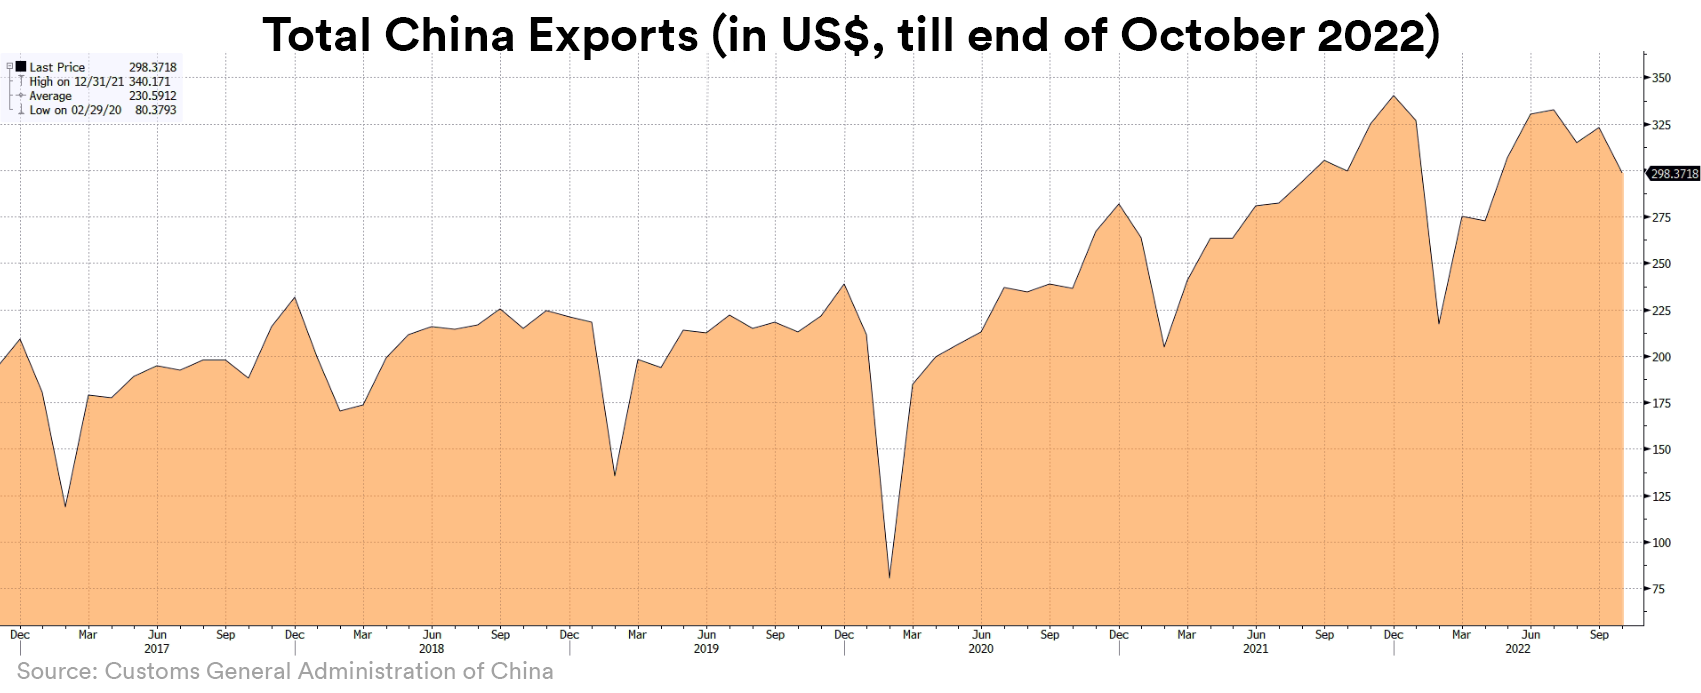
As of end of October, China's total exports have seen a 3-month decrease, with the devaluation of the yuan in order to boost exports not playing a significant role in propping this value.
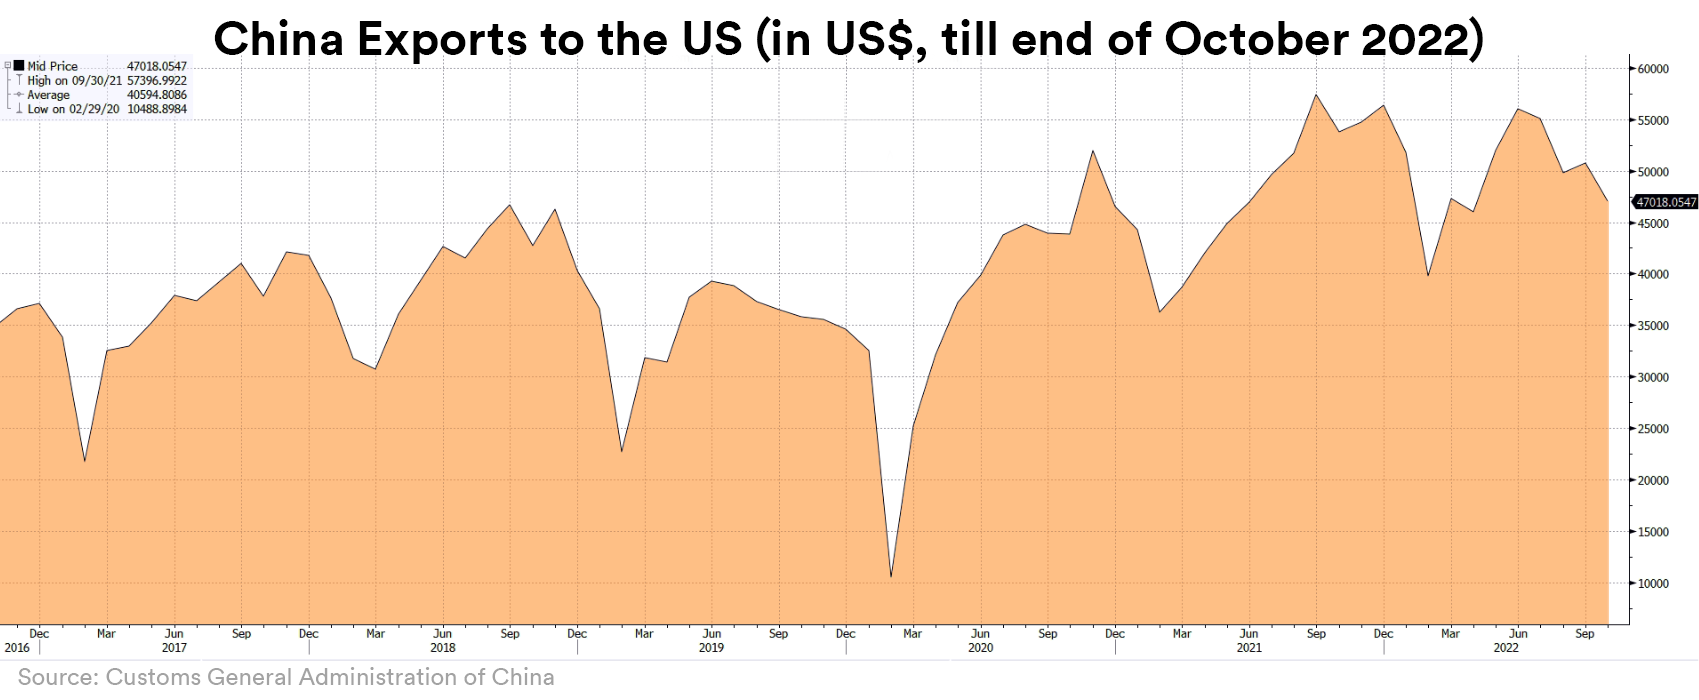
China's exports to the US, in terms of unit volumes, typically tend to be the likes of consumer goods, components and raw material. Over the 5 months leading to October, this has seen a steady downward trend.
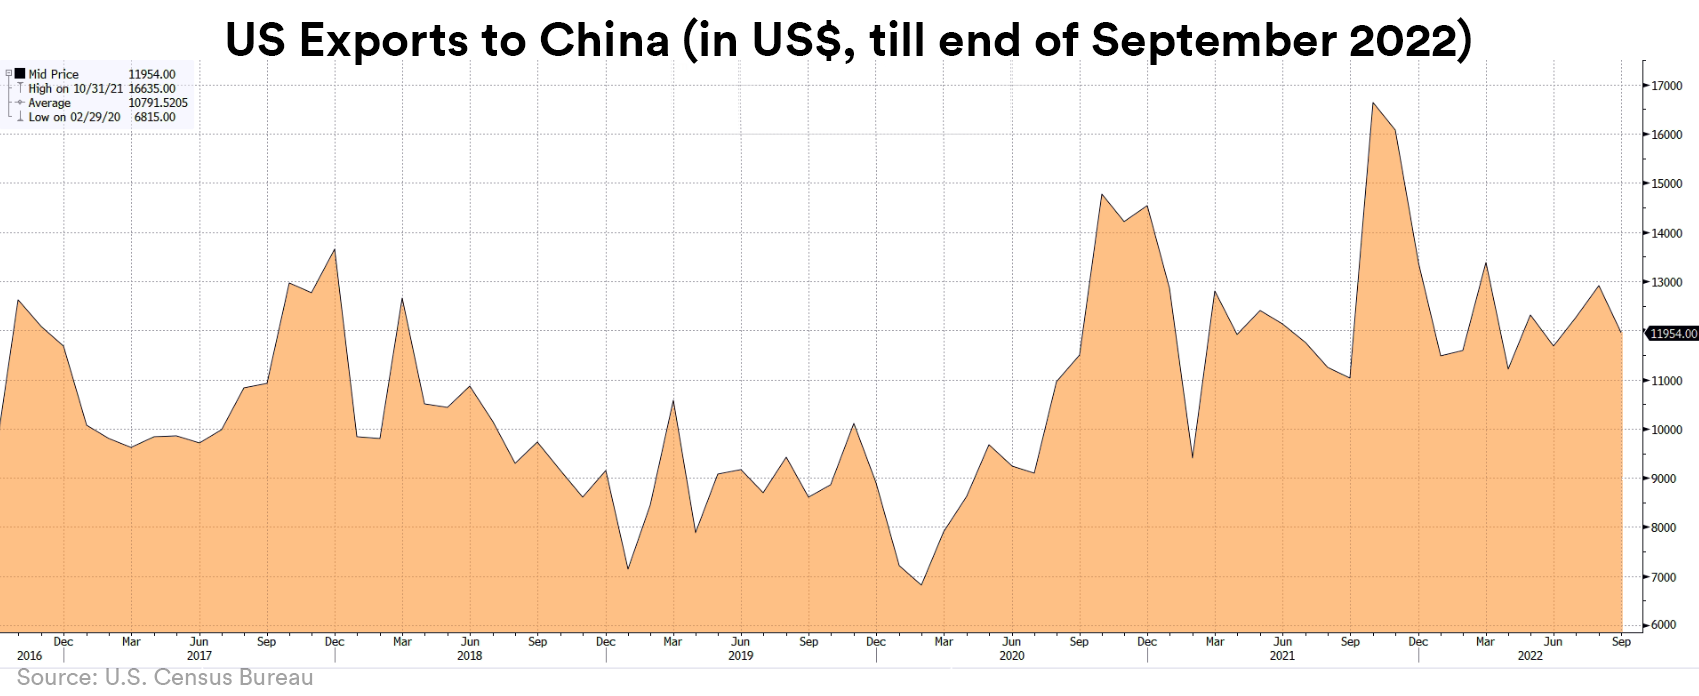
The US principally exports machinery and natural resources to China. These have been going strong but it did witness a sudden downturn starting from the end of August.
The consumer-producer interplay is problematic for China, which counts exports as one of its economic pillars. With flagging domestic demand - as evidenced by the initiatives to boost domestic spending - and crumbling growth rates in infrastructure (another economic pillar), higher export volumes would be needed. With flagging consumption in the Western Hemisphere, this becomes another avenue that will weigh down its economic goals.
Many investment managers consider investing in Chinese markets to offer adequate diversification from their exposure to US markets. As a result, Chinese equities received heavy volumes and higher valuations. As present circumstances indicate, this notion isn't necessarily a robust one. There's every expectation that any downward pressure on US equities (which is being expected) will also lead to downward pressure on the Chinese economy, which already have a number of points of concern.
Exchange-Traded Products (ETPs) offer substantial potential to gain magnified exposure with potential losses limited to only the invested amount and no further. Learn more about Exchange Traded Products providing exposure on either the upside or the downside to the S&P 500 as well as the upside or the downside to the MSCI China Index.
Capitale a rischio. Potreste perdere tutto il vostro investimento. Consultate l'avvertenza completa sui rischi qui.
 Market Insights

