Capital à risque. Vous pouvez perdre la totalité de votre investissement. Consultez l'avertissement complet sur les risques ici.
Key Takeaways
· UnitedHealth beat Q3 forecasts and raised 2026 profit guidance.
· Lower medical costs boosted margins despite falling membership.
· Rising costs and regulatory risks remain key challenges for 2027.
UnitedHealth Group beat Wall Street third-quarter 2026 forecasts on the 13th of October and raised its full-year profit outlook for the third time this year.1 Adjusted earnings per share (EPS) came in at $4.69 against a $4.12 consensus, and 2026 guidance now stands at no less than $20.50.1 Here's what drove the beat, what changed, and what it could mean for UNH investors.
UnitedHealth Q3 2026 at a Glance
· Earnings beat: adjusted EPS of $4.69 vs $4.12 expected; revenue of $112.7 billion vs $111.0 billion.1
· Margin recovery: the medical care ratio fell to 88.4% from 89.9%, helped by $610 million of reserve releases.1
· Guidance raised: 2026 adjusted EPS of at least $20.50, up from $19.50–$20.00.1
· Weak spot: members fell to 48.3 million from 50.1 million a year earlier.
· Stock reaction: shares have risen more than 7% after brokers lifted targets.
This was a margin-recovery quarter, not a growth quarter. Revenue actually slipped 0.4% year on year as UnitedHealthcare shed members on purpose. But earnings from operations jumped 52% to $6.6 billion, and the repair job that began after the 2025 collapse is now visible in every segment.1
UnitedHealth Q3 2026 Earnings Are Up 61% Amid Easing Medical Costs
Adjusted EPS rose 61% to $4.69 from $2.92, while GAAP EPS climbed to $4.56 from $2.59. Net margin nearly doubled to 3.6% from 2.1%.1 Net earnings attributable to shareholders reached $4.1 billion, up from $2.3 billion a year earlier.2
The important medical care ratio (MCR) is at 88.4%, below analyst forecasts.3 Management credited cost management, benefit cuts and pricing discipline. However, the quarter included $610 million of favourable prior-period reserve development for 2026 dates of service, which flattered the ratio.1 The operating cost ratio also improved to 12.8% from 13.5%.1
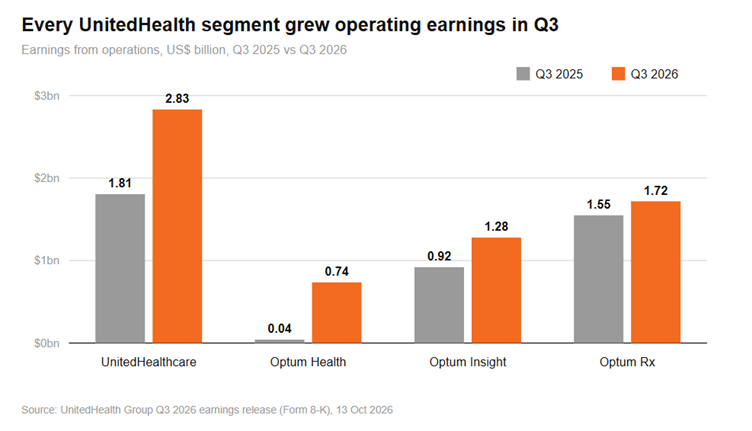
Optum Health is the standout turnaround. Revenue fell 10% as the unit exited value-based care markets where it lacked scale, yet operating earnings rose almost eighteen-fold to $735 million.1 Optum Rx benefited from biosimilar adoption, although adjusted scripts dropped to 393 million from 414 million.1
The soft spot was membership. UnitedHealthcare served 48.3 million people, below the 48.6 million analysts expected and down from 50.1 million a year ago.2 Medicare Advantage enrolment has contracted by 935,000 since year-end 2025. Cash flow from operations was $5.1 billion, or 1.2x net income.1
Why the Medical Care Ratio is Important for UNH Stock
The medical care ratio (MCR) shows how much of each premium dollar UnitedHealth spends on patient care. At 88.4%, about 88 cents of every dollar went on medical costs, leaving the rest for running costs and profit.
Small moves matter at this scale. On roughly $87 billion of quarterly premiums, a one-point drop in the MCR frees up close to $0.9 billion of profit before tax.1 That is why investors watch this one number more closely than revenue.
UnitedHealth Raises 2026 Earnings Guidance
The strongest signal from the report was the improved full-year outlook. UnitedHealth raised its forecast for 2026 adjusted earnings to at least $20.50 per share, up from its previous range of $19.50 to $20.00. The revised target also exceeded the analyst consensus of approximately $19.86 before the announcement.1
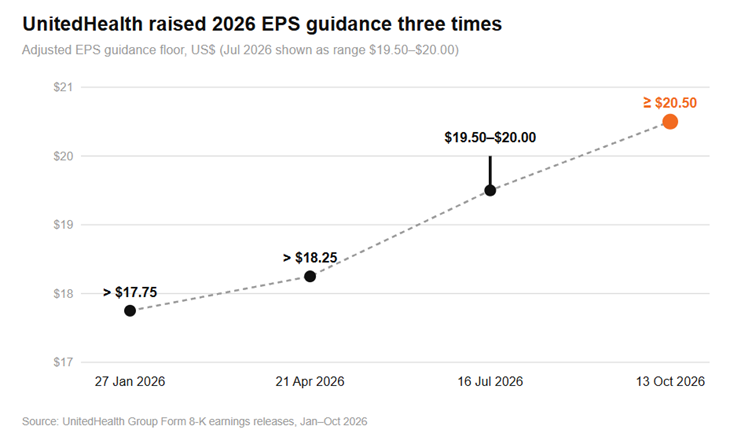
The raise is cautious in shape. Nine-month adjusted EPS already stands at $18.30, so the floor implies only about $2.20 for the fourth quarter. That leaves room for typical Q4 seasonality in Optum Health, plus extra technology spending, which management flagged on the call. It also leaves room for another upside surprise in January.
Capital returns remain intact. The company bought back $5.0 billion of stock and paid $6.2 billion of dividends through September. Debt-to-capital was 41.7%, against a target of about 40% by year-end.1
What Changed at UnitedHealth in Q3?
Commercial medical costs remain the main pressure point. UnitedHealthcare CEO Tim Noel said commercial cost trend is running above the company's initial 11% assumption, driven by specialty drugs, higher clinician costs and No Surprises Act arbitration. He conceded this pushes out the timeline for long-term commercial margin targets and stressed that the trend is stabilising, not accelerating. Employer attrition also cost 165,000 members in the quarter.1
Medicare Advantage: smaller, but more profitable. The deliberate shrink-to-profit strategy continues, with 935,000 fewer MA seniors since year-end 2025.1 According to executives Medicare margins should end 2026 near the top of the 2-4% target range.
Medicaid is still a drag. Core Medicaid margins should improve only to modestly better than −1% for 2026, with a return to target margins aimed for 2028.
Optum Health's repair is ahead of schedule. Leaving sub-scale value-based care markets lifted the margin to 3.2%, against a 6-8% target for 2028. Optum Insight's AI-driven Integrity One platform has grown from two live clients at the end of 2025 to 15, with 24 more in progress.
Reputation and regulatory reset. Management is cutting 30% of prior-approval volume by end-2026, has launched a fee-based, transparent PBM model and plans 100% rebate pass-through by January 2028.1 It is also rebating 2026 ACA individual-market profits to about 1 million members. The Justice Department legal actions over UnitedHealth's Medicare business remain an unresolved overhang.
UNH Stock Forecast 2027: What Do Analysts Expect?
The Street's verdict is constructive: most large brokers kept buy-equivalent ratings and several raised targets after the print. CFO DeVeydt said the low end of the 13–16% long-term EPS growth target is a reasonable starting point for 2027 and hinted that consensus may understate the opportunity. Applied to the $20.50 floor, 13% growth implies roughly $23.15 of 2027 adjusted EPS, above the $22.61 consensus. A fuller 2027 outlook is due before year-end.
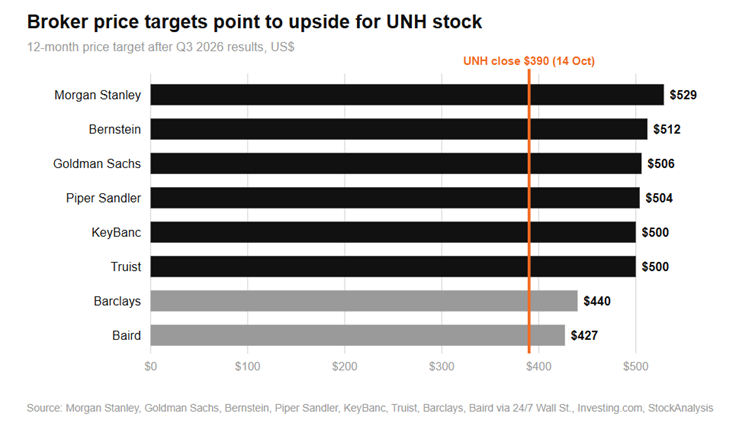
The bull case rests on margin repair. Morgan Stanley argues that the UnitedHealthcare-Optum combination is hard to copy and that cost normalisation should pull margins back toward historical levels.4 Goldman Sachs, per a published summary of its note, sees further profit leverage in Optum Health, commercial and Medicaid.5 Piper Sandler values the shares at 18x estimated 2028 EPS.6 At about 17x forward earnings, the stock trades below its own history.
The bear case is about growth and quality. Membership keeps shrinking, and the stock is down roughly 10% over three months even as rivals held steady. The Q3 MCR beat leaned on $610 million of reserve releases, which will not repeat on schedule. Commercial cost trend, Medicaid funding, Star ratings and the DOJ investigation are the swing factors for 2027.
UnitedHealth has now beaten and raised three times in 2026, and the profit recovery looks durable. The next catalyst is the full 2027 outlook due before year-end, where investors will want proof that earnings can grow even while enrolment does not.
Professional investors looking for magnified exposure to UnitedHealth may consider Leverage Shares +3x Long UnitedHealth ETP.
Footnotes
1. UnitedHealth Group Press Release, UnitedHealth Group Reports Third Quarter 2026 Results, as of October 13, 2026.
2. Fierce Healthcare, UnitedHealth Group execs detail continued improvements at Optum Health, as of October 13, 2026.
3. Finviz, UnitedHealth Group Raises 2026 Profit Outlook After Third-Quarter Earnings Beat, as of October 13, 2026.
4. Investing, UnitedHealth is Down Big Over 3 Months: A Big Bank Says 40% Gains to Come After Raising Their Target, as of October 14, 2026.
5. TechFlow, Goldman Sachs: UNH Q3 EPS $4.69 Beats Expectations, Price Target Raised to $506, as of October 15, 2026.
6. Investing.com, Piper Sandler raises UnitedHealth stock price target to $504, as of October 14, 2026.
Capital à risque. Vous pouvez perdre la totalité de votre investissement. Consultez l'avertissement complet sur les risques ici.
 Market Insights