Capital à risque. Vous pouvez perdre la totalité de votre investissement. Consultez l'avertissement complet sur les risques ici.
S&P 500 at a fresh record high.
Inflation remains elevated.
U.S. GDP growth is solid.
Fed in no rush to cut rates.
S&P 500 at new record highs as tech stocks extend gains
With the S&P 500 trading at a new all-time high of 5,149 reached on Monday, investor sentiment remains bullish. The U.S. benchmark index has extended gains further after U.S. inflation data released last week came in-line with estimates, cementing expectations of an interest rate cut in June - July.
Thanks to the tight labour market that kept wages elevated, which supported consumer spending, the economy has defied warnings of a recession after the Federal Reserve aggressive interest rates campaign to combat inflation.
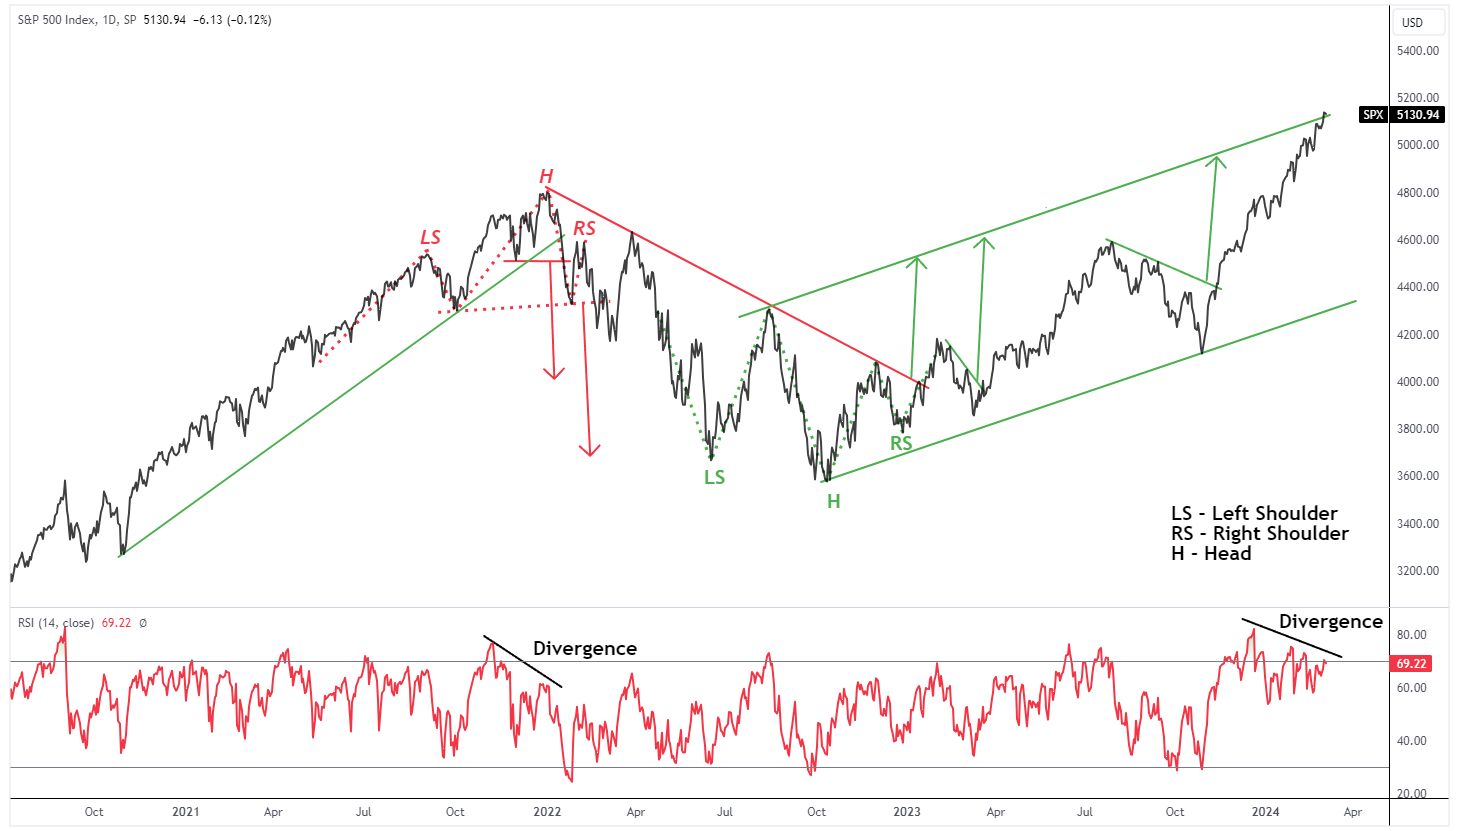
The market has rallied strongly since its October 2022 low, propelled by euphoria around artificial intelligence chips demand. However, investors are now questioning how long the impressive pace of gains could last. While at this point there are no clear signs the rally is reversing, there are several red lights flushing on the charts.
First, the current price action has rebounded to its up trend channel line crossing at 5,130 where initial profits taking could arise. Second, a triple bearish divergence between the price and the Relative Strength Index indicator has formed, suggesting that internal momentum conditions are deteriorating, and the rally is vulnerable to a pull back in the short-term. Over the long-term, we continue to be positive and see levels to 5,400 – 5,450 as easily achievable.
Source: TradingView
Sticky inflation poses challenge for the U.S economy
Investors are concerned that inflation could remain elevated amid high government spending, strong consumer, and resilient labour market. Such situation may influence the Federal Reserve to keep interest rates elevated for a longer period of time.
Geo-political tensions which could escalate further are headwinds to global trade and could cause surges in inflation. Such potential risks do not seem to have influenced market bulls so far, which have been carried away with the artificial intelligence hype.
Apart from the robust labour market, strong government spending, geo-political and inflation risk, the market is facing global trade uncertainties associated with the U.S. presidential elections in November.
GDP growth remains strong
U.S. economic growth in the fourth quarter was lowered slightly, but its composition was much stronger than initially expected, which bodes well for the near-term outlook on the market.
According to the Bureau of Economic Analysis the second estimate of fourth-quarter GDP increased at a 3.2% annual rate, slightly revised down from the previously quarter 3.3% growth.
Consumer spending, which accounts for more than two-thirds of U.S. economic activity was stronger than initially thought, increased at a rate of 3.0% vs. 2.8% expected.
Inflation and Interest rates outlook
Investors remain concerned about the possibility that the Federal Reserve will keep interest rates at elevated levels for a prolonged period of time, and thus the focus has been on a string of key economic readings that could dictate Fed thinking going forward.
The latest Personal Consumption Expenditures (PCE) index came broadly in line with expectations, with the Core PCE for January arriving at 2.8% declining from 2.9% in December. This marks the 12 thconsecutive decline in Core PCE and could be described as a consistent movement towards the Federal Reserve's 2% inflation target.
The annual Consumer Price Index (CPI) came at a 3.1% in January 2024, while core CPI which excludes the volatile food and energy costs was 3.9% showing small disinflation over the past few months.
Several rate cuts are expected in 2024, and cooling inflation would be the most important signal to the Federal Reserve that the U.S. economy is ready for softer interest rates. Before its next meeting on the 20 thof March the Fed will examine the release of another CPI update, which is due on the 12 th of March.
Over the past two years the U.S. central bank has raised its policy rate by 525 basis points to the current range of 5.25%-5.50%. The pick-up in inflation at the beginning of the year, has pushed back rate-cut expectations from May to June.
Conclusion
Uncertainties regarding inflation, interest rate cuts, and geo-political risks are among the most prominent factors influencing the stock market currently. Despite all the challenges the market faces U.S. equities are trading at record highs. While a correction could unfold to unwind the overbought momentum conditions, we see further upside potential over the medium to long-term.
Capital à risque. Vous pouvez perdre la totalité de votre investissement. Consultez l'avertissement complet sur les risques ici.
 Market Insights