Capital en riesgo. Puede perder la totalidad de su inversión. Consulte la advertencia de riesgo completa aquí.
Ferrari Earnings Reaffirm the Power of Scarcity as 2026 Profit Growth Comes into View
Ferrari’s latest earnings release has provided a timely reminder of the company’s structural strengths. The Italian luxury carmaker beat fourth-quarter expectations, closed 2025 with expanding margins, and guided for profit growth in 2026, easing investor concerns after a difficult 2025 for the stock.
Shares responded sharply, rising more than 10% intraday, as the results reaffirmed Ferrari’s ability to grow earnings without relying on higher volumes.
Fourth-Quarter Results Beat Expectations Despite Lower Shipments
Ferrari delivered better-than-expected fourth-quarter earnings even as vehicle shipments declined year on year. Forth quarter deliveries fell to 3,152 vehicles, down 173 units from the same period last year, reflecting deliberate volume discipline rather than weakening demand.
Regional trends were mixed. Shipments in Europe, the Middle East and Africa were flat at 1,550 vehicles, while the Americas saw an 8.2% decline. Greater China experienced a sharper contraction, with deliveries falling 36%, while the rest of Asia-Pacific posted modest growth.
Despite these headwinds, revenue increased in the quarter, supported by a richer product mix and higher levels of customisation which is a recurring theme in Ferrari’s earnings profile.
2025 Financial Performance Shows Margin Expansion
For the full year, Ferrari reported a strong set of financial results:
Net revenues: €7.15 billion, up 7% year on year (8% at constant exchange rates)
EBIT: €2.11 billion, up 12%, with a margin of 29.5%
EBITDA: €2.77 billion, up 8%, with a margin of 38.8%
Net profit: €1.6 billion, up 5%
Diluted EPS: €8.96
Revenue from cars and spare parts exceeded €6.0 billion, growing nearly 5%, driven by favourable product and geographic mix as well as strong demand for personalised vehicles. Sponsorship, commercial and brand-related revenues surpassed €800 million, rising 22% year on year, supported by racing activities and lifestyle initiatives.
Margins expanded despite higher operating costs and increased investment in innovation, highlighting Ferrari’s pricing power and cost control.
Cash Generation and Balance Sheet Remain Key Strengths
Ferrari’s ability to convert earnings into cash continues to distinguish it from much of the automotive sector. Industrial free cash flow exceeded €1.5 billion in 2025, even after capital expenditures of around €950 million.
Net industrial debt fell further to just €32 million by year-end, despite total shareholder returns, including dividends and share buybacks, exceeding €1.3 billion during the year. This balance sheet strength provides flexibility as Ferrari enters a heavy investment phase.
2026 Guidance Signals Continued Profit Growth
Looking ahead, Ferrari expects revenue and earnings to rise again in 2026, supported by new model launches and sustained demand for higher-margin vehicles.
Management guided for:
Revenue of around €7.5 billion
EBITDA of more than €2.93 billion
EBITDA margin of approximately 39%
This compares with EBITDA of €2.77 billion in 2025, implying modest but meaningful profit growth. While higher investments, depreciation and currency headwinds are expected to weigh on results, Ferrari remains confident that product mix and personalisation will offset these pressures.
The order book now extends toward the end of 2027, reinforcing long-term visibility and reflecting Ferrari’s continued discipline in managing demand.
Volume Discipline Continues to Define the Strategy
Deliveries for 2025 were intentionally kept broadly flat at 13,640 units, allowing Ferrari to manage a significant model change-over that will continue into 2026. New models launched during the year are expected to impact deliveries and revenues going forward, supporting margins rather than volume expansion.
At the same time, racing revenues and lifestyle activities are expected to contribute further to top-line growth, broadening the earnings base beyond car sales alone.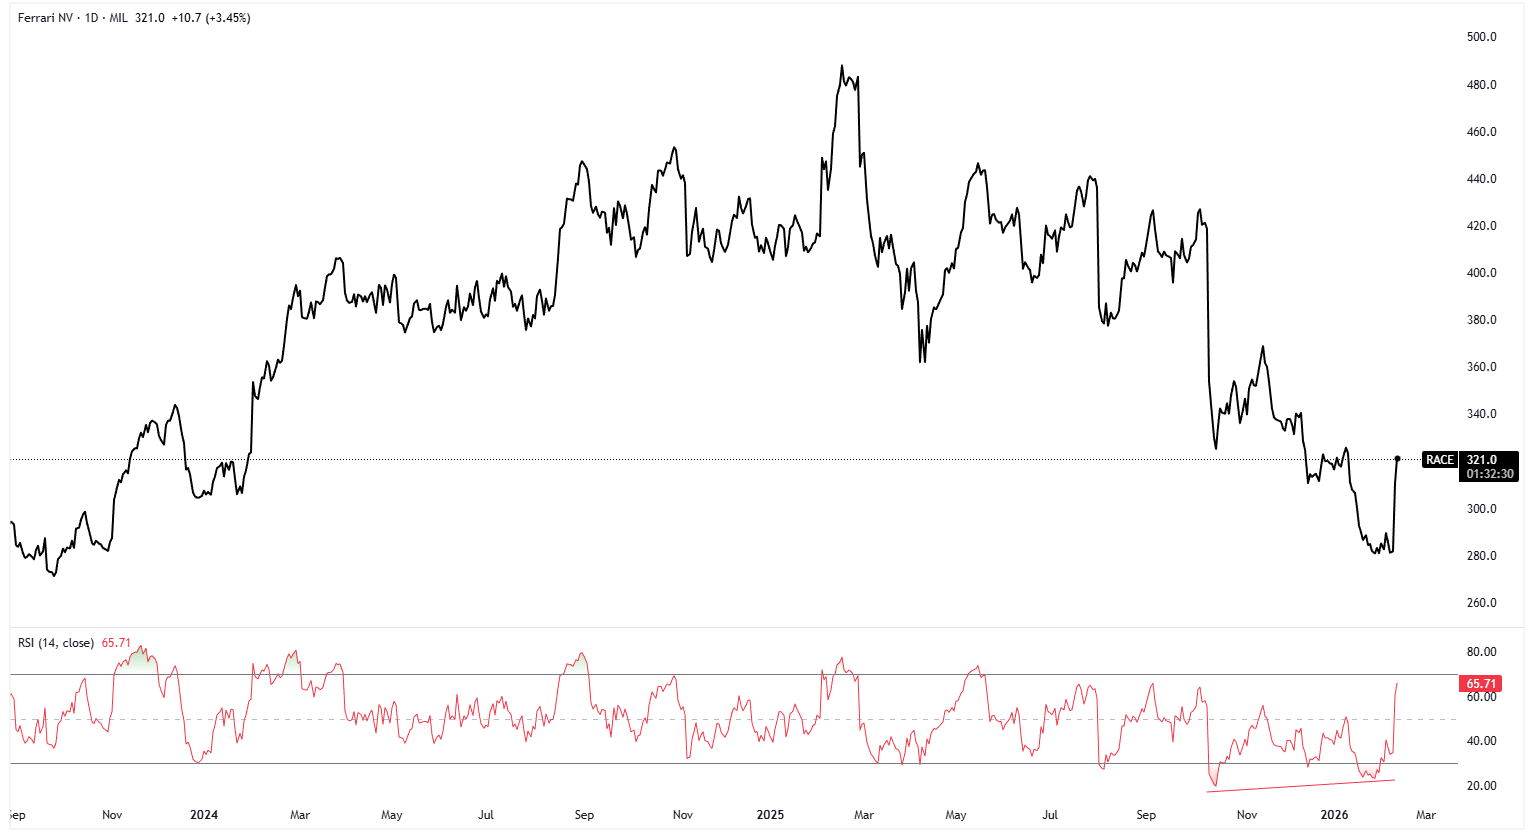
Source: TradingView. Ferrari daily price chart as of 11 February 2026.
Execution, Not Expansion, Is the Key Variable
Ferrari’s latest results highlight a business that continues to prioritise value over volume. Earnings growth is being driven by mix, pricing and brand monetisation rather than higher shipments. This model has proven resilient even amid regional demand volatility and currency pressures.
Ferrari stands out as a company where execution and capital discipline remain central. With margins still expanding and profit growth guided for 2026, the company enters the next phase of its cycle with confidence and on its own terms.
Ferrari shares declined 44% from its record high of €492.80 in February 2025 to a low of €276.20 last Friday. In our view, this selloff appears overdone and we see a strong likelihood of the price rallying to €440 in the next 12 months, offering investors a potential 45% from current price levels.
Earnings momentum is turning and valuation pressure is easing, leaving Ferrari well positioned for a re-rating as disciplined execution drives profit growth and shareholder returns into 2026.
Professional investors looking for magnified exposure to Ferrari may consider Leverage Shares +3x Long Ferrari ETP or -3x Short Ferrari
Capital en riesgo. Puede perder la totalidad de su inversión. Consulte la advertencia de riesgo completa aquí.
 Market Insights