Article by Edward Sheldon
Anthropic IPO: The S-1 Prospectus Summarized
November 3, 2026 | Research Insights
In late October, AI powerhouse Anthropic filed its S-1 prospectus1 with the US SEC, confirming that it plans to go public this year. This sent investors into a frenzy, as we could potentially be looking at one of the largest IPOs of all time.
To help unpack the 300+ page S-1 prospectus for investors, we’ve broken the filing down into five essential charts. Here’s what you need to know about Anthropic’s revenue, compute spending, and profitability.
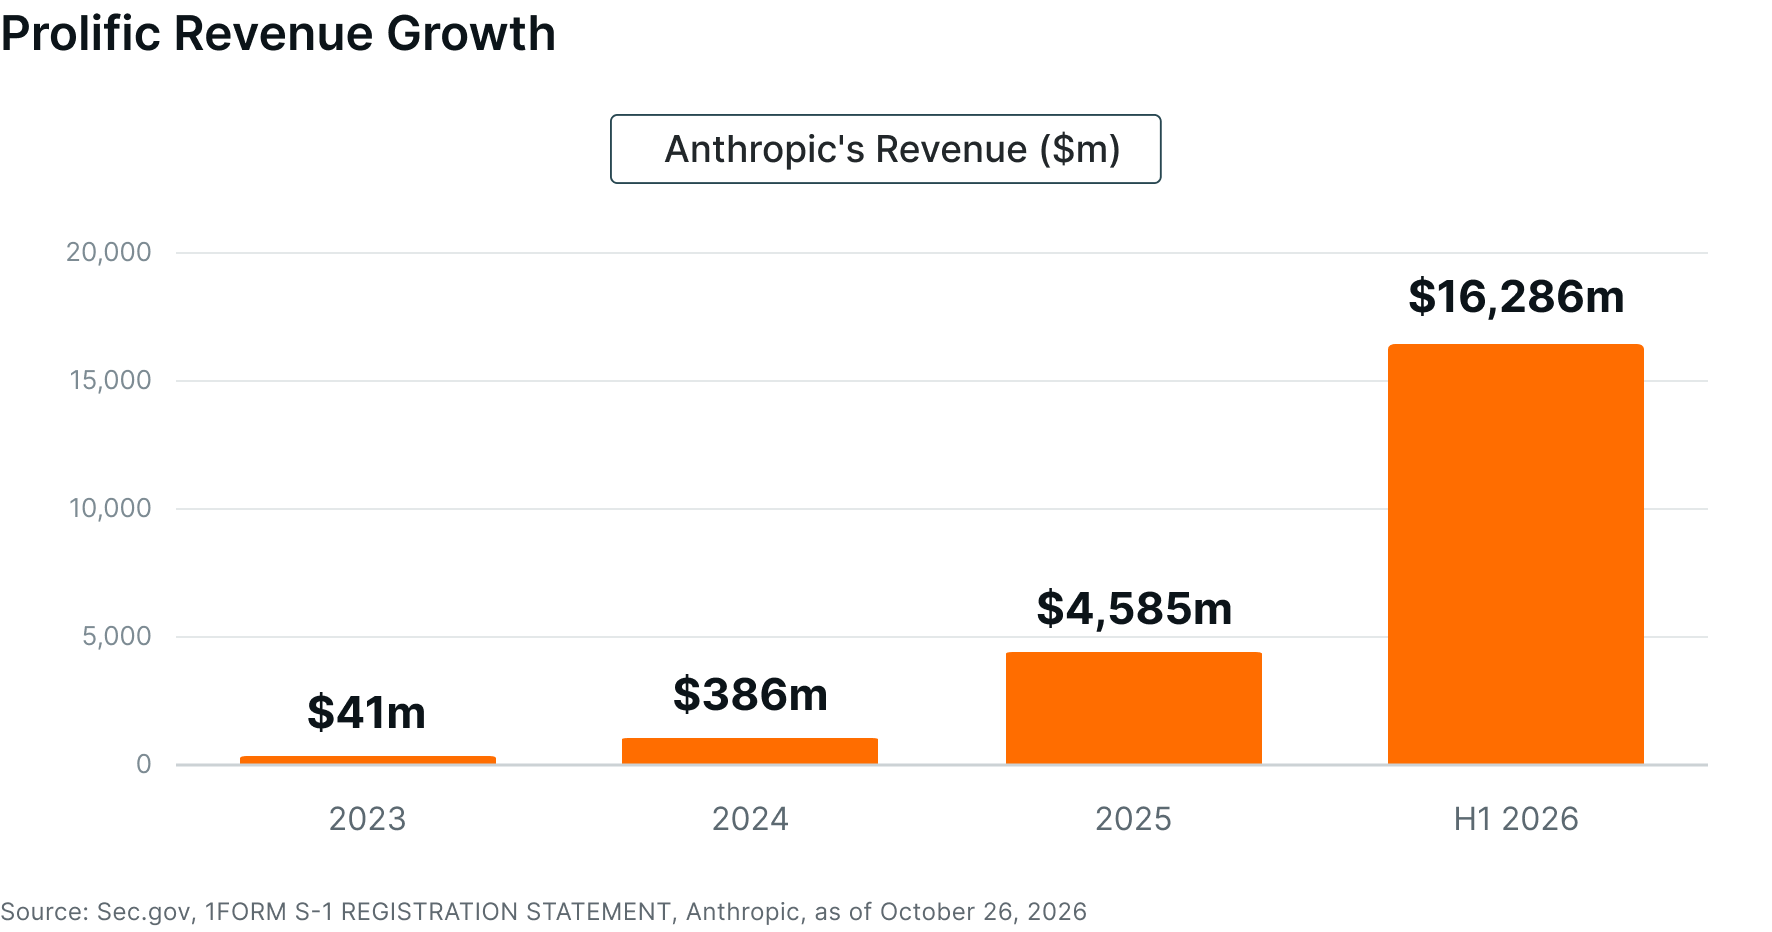
Anthropic’s revenue growth in recent years has been phenomenal. In the first half of 2026, the AI lab generated revenue of $16.3 billion – an increase of 1,300% year-over-year and up 255% on the figure for the whole of 2025.
To put that in perspective, Palantir and CrowdStrike generated top-line growth of 89% and 26% respectively for the first half of the current fiscal year2. So, the AI lab is growing at a far faster clip than these publicly traded AI software companies.
As for what’s driving this spectacular top-line growth, it’s demand for its Claude model from enterprises. They are choosing Claude over other models due to its capabilities and built in AI safety.
Note that enterprises tend to have large software budgets – the S-1 showed that Anthropic already has over 250 customers spending $10 million a year on its services. They also tend to be a source of recurring revenues.
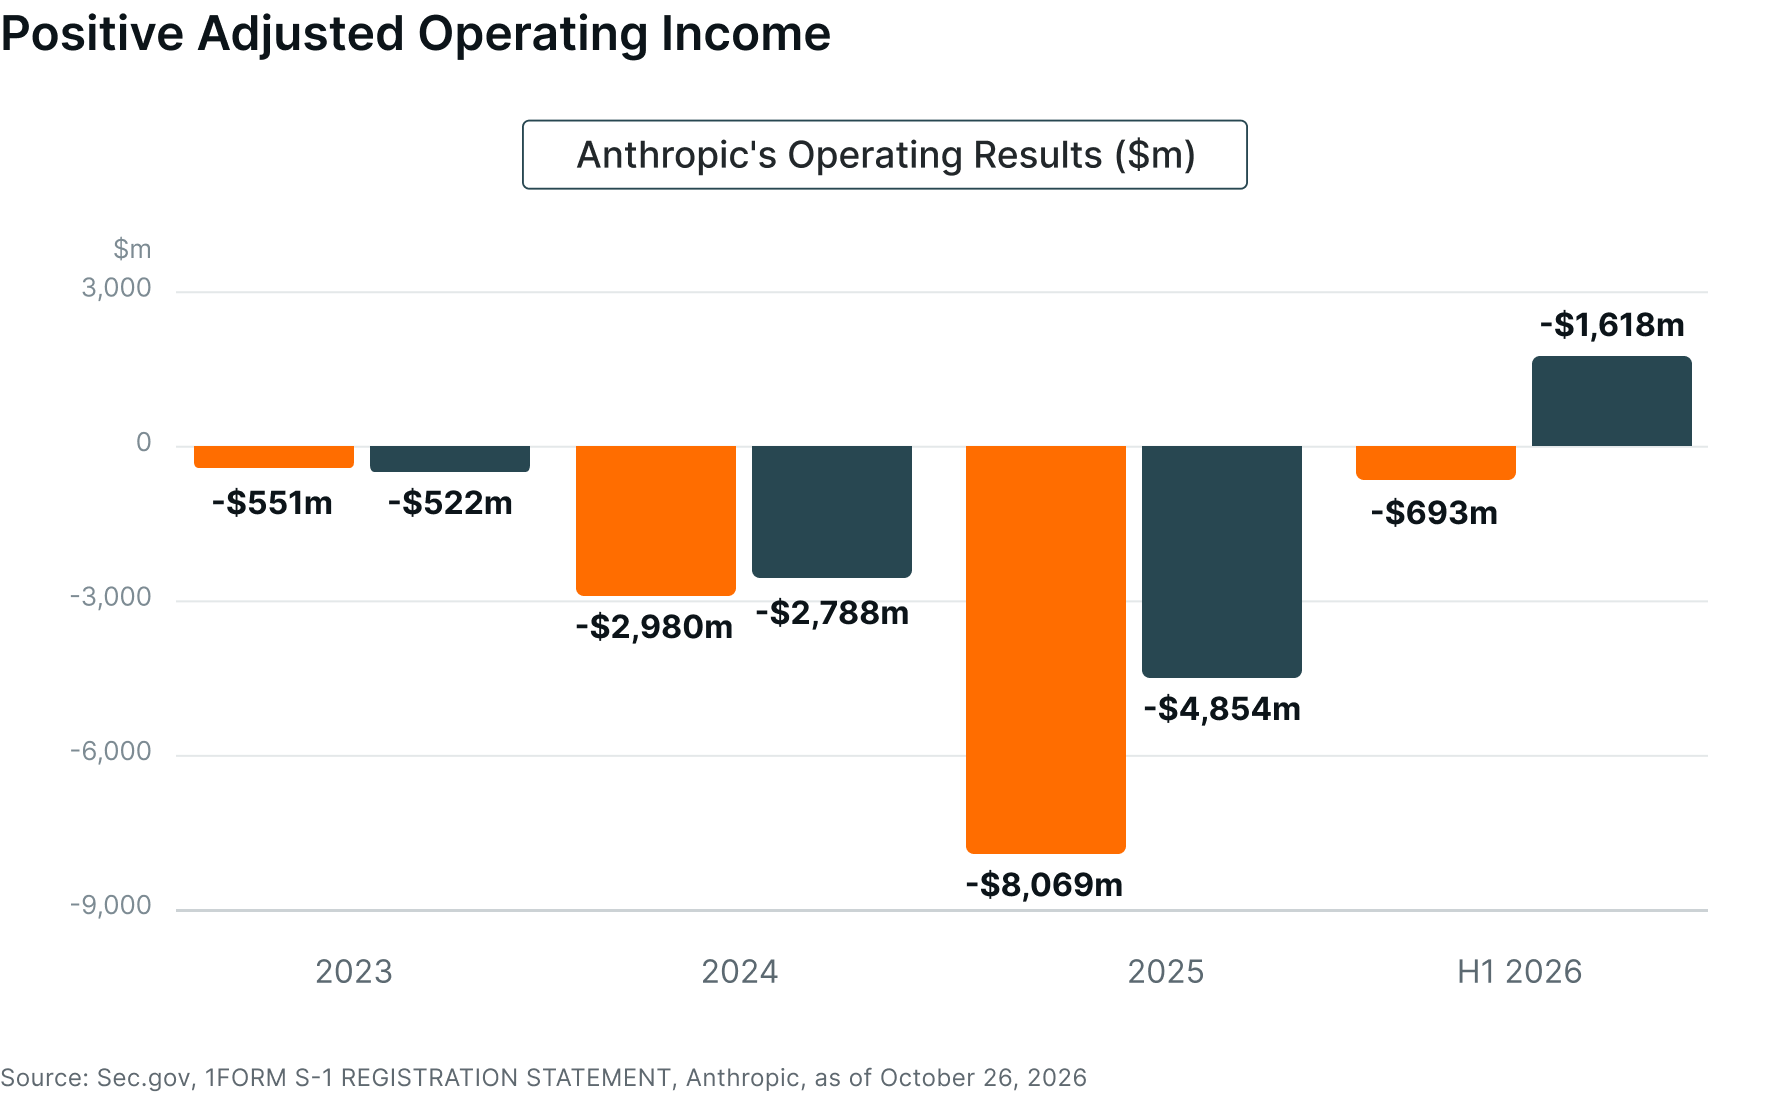
Anthropic has a history of generating operating losses. That’s because it is continually spending significant amounts of money on compute and AI infrastructure.
However, recently, its operating losses have narrowed dramatically. For the first half of 2026, for example, its operating loss was just $693 million (versus $8.1 billion in 2025).
Meanwhile, for the first half of 2026, adjusted operating income was positive. It came in at $1.6 billion for the period.
Now, there are no guarantees that the AI lab will continue to generate positive adjusted operating income. However, the first-half performance shows that the company is capable of generating profitability, at least on an adjusted basis.
Huge Net Losses
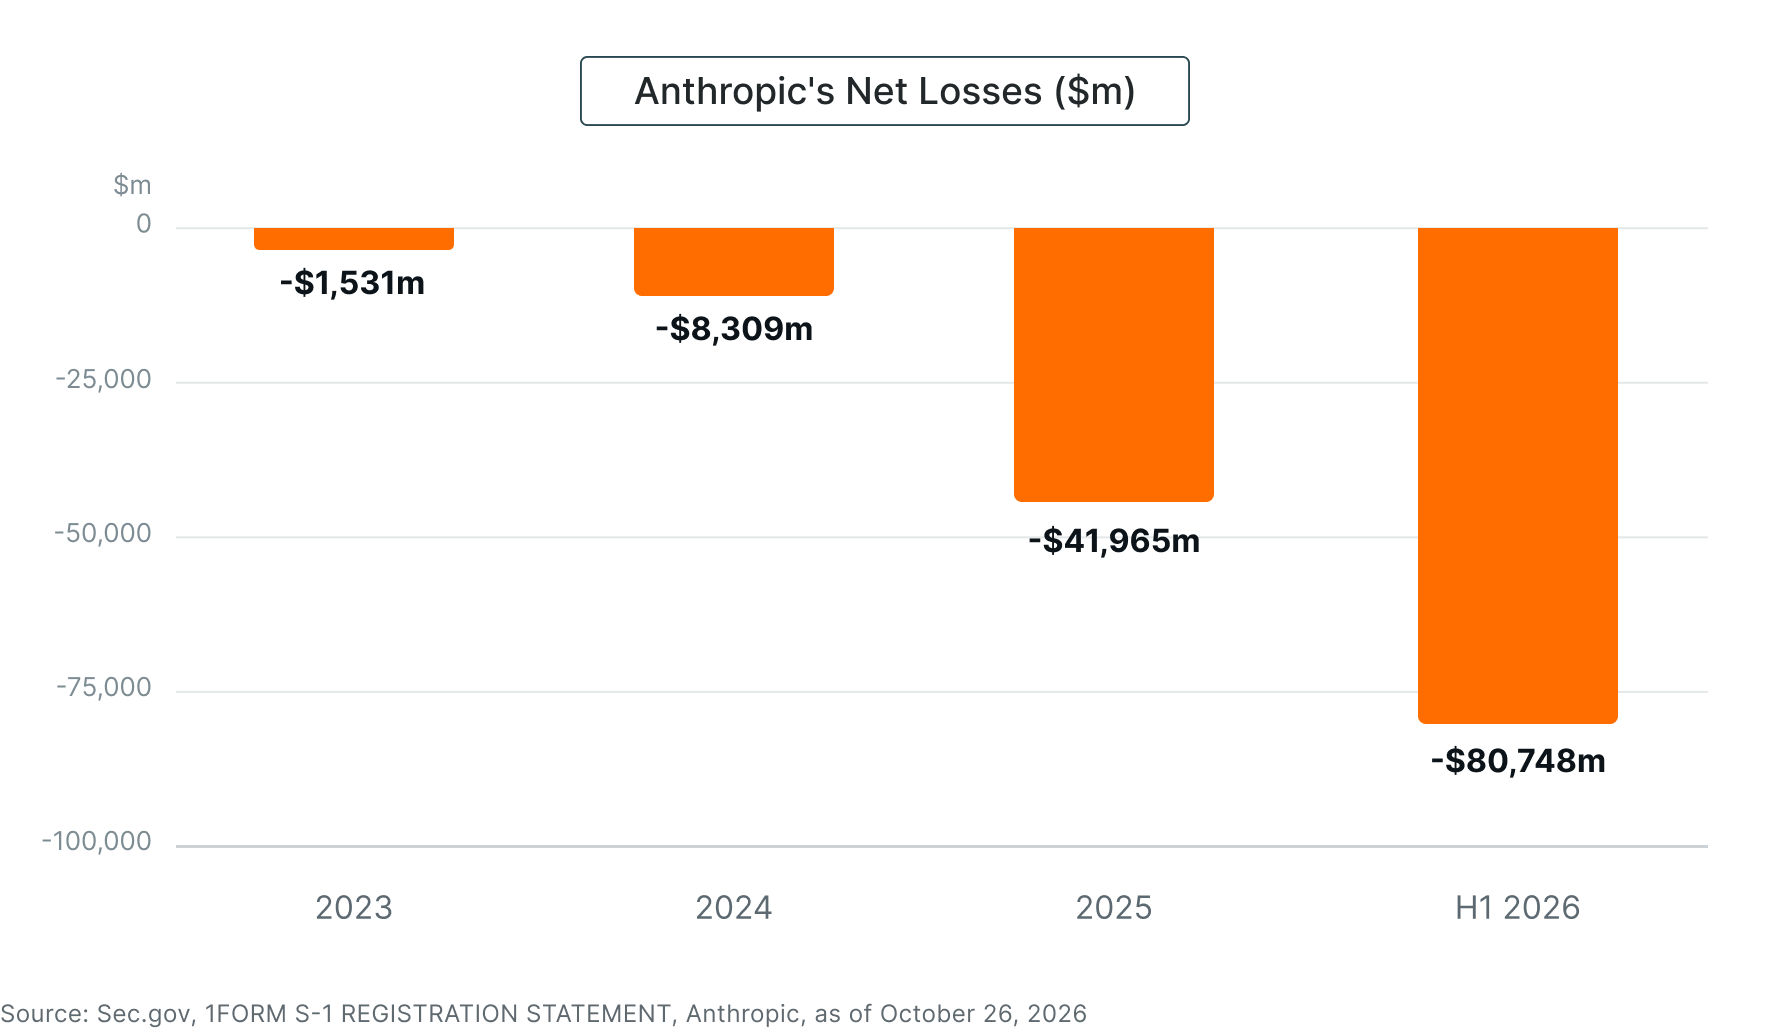
At first glance, net losses in the S-1 filing looked concerning. For the first half of 2026, for example, the company’s net loss was $81 billion.
However, digging deeper, the picture doesn’t look so bad. Because the vast majority of that H1 loss was the result of changes in fair value of convertible notes, derivative liabilities, and Simple Agreements for Future Equity (SAFEs).
With Anthropic’s valuation surging over the period, the paper value of the equity-linked debt and agreements it previously issued also jumped. This increase in value was recorded as a $72.4 billion financial charge.
Assuming the company’s valuation doesn’t continue skyrocketing, these kinds of charges should moderate at some stage. This should help its profitability position.
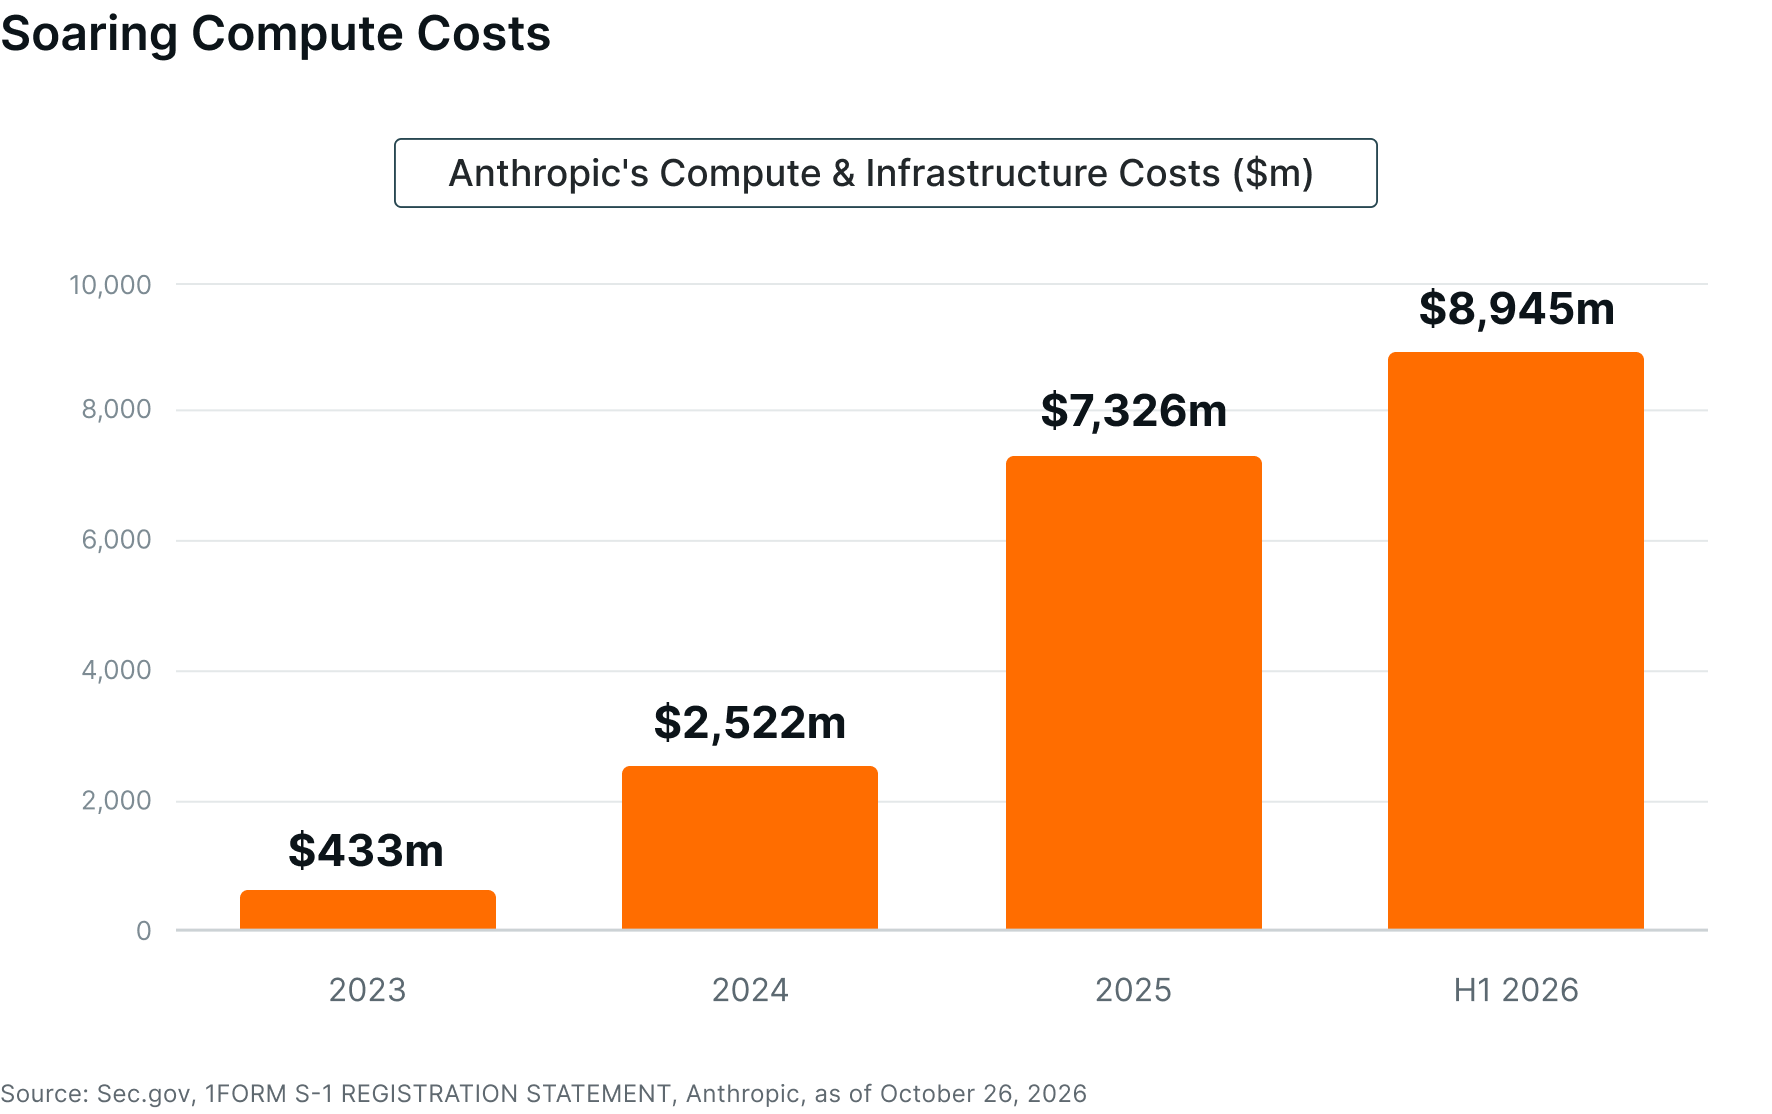
One of the reasons that Anthropic has struggled to generate profitability in the past is that its compute costs are enormous. This was highlighted in its S-1 filing.
For the first half of 2026, its compute bill amounted to $8.9 billion. That was 22% higher than its compute bill for the whole of 2025.
Looking ahead, the company expects to continue spending heavily on compute. In an amended IPO filing3, it lists about $895 billion of compute commitments.
Of that, about $70 billion comes due within a year. This spending on compute is a major area of focus for the bears – it adds uncertainty to the investment case.
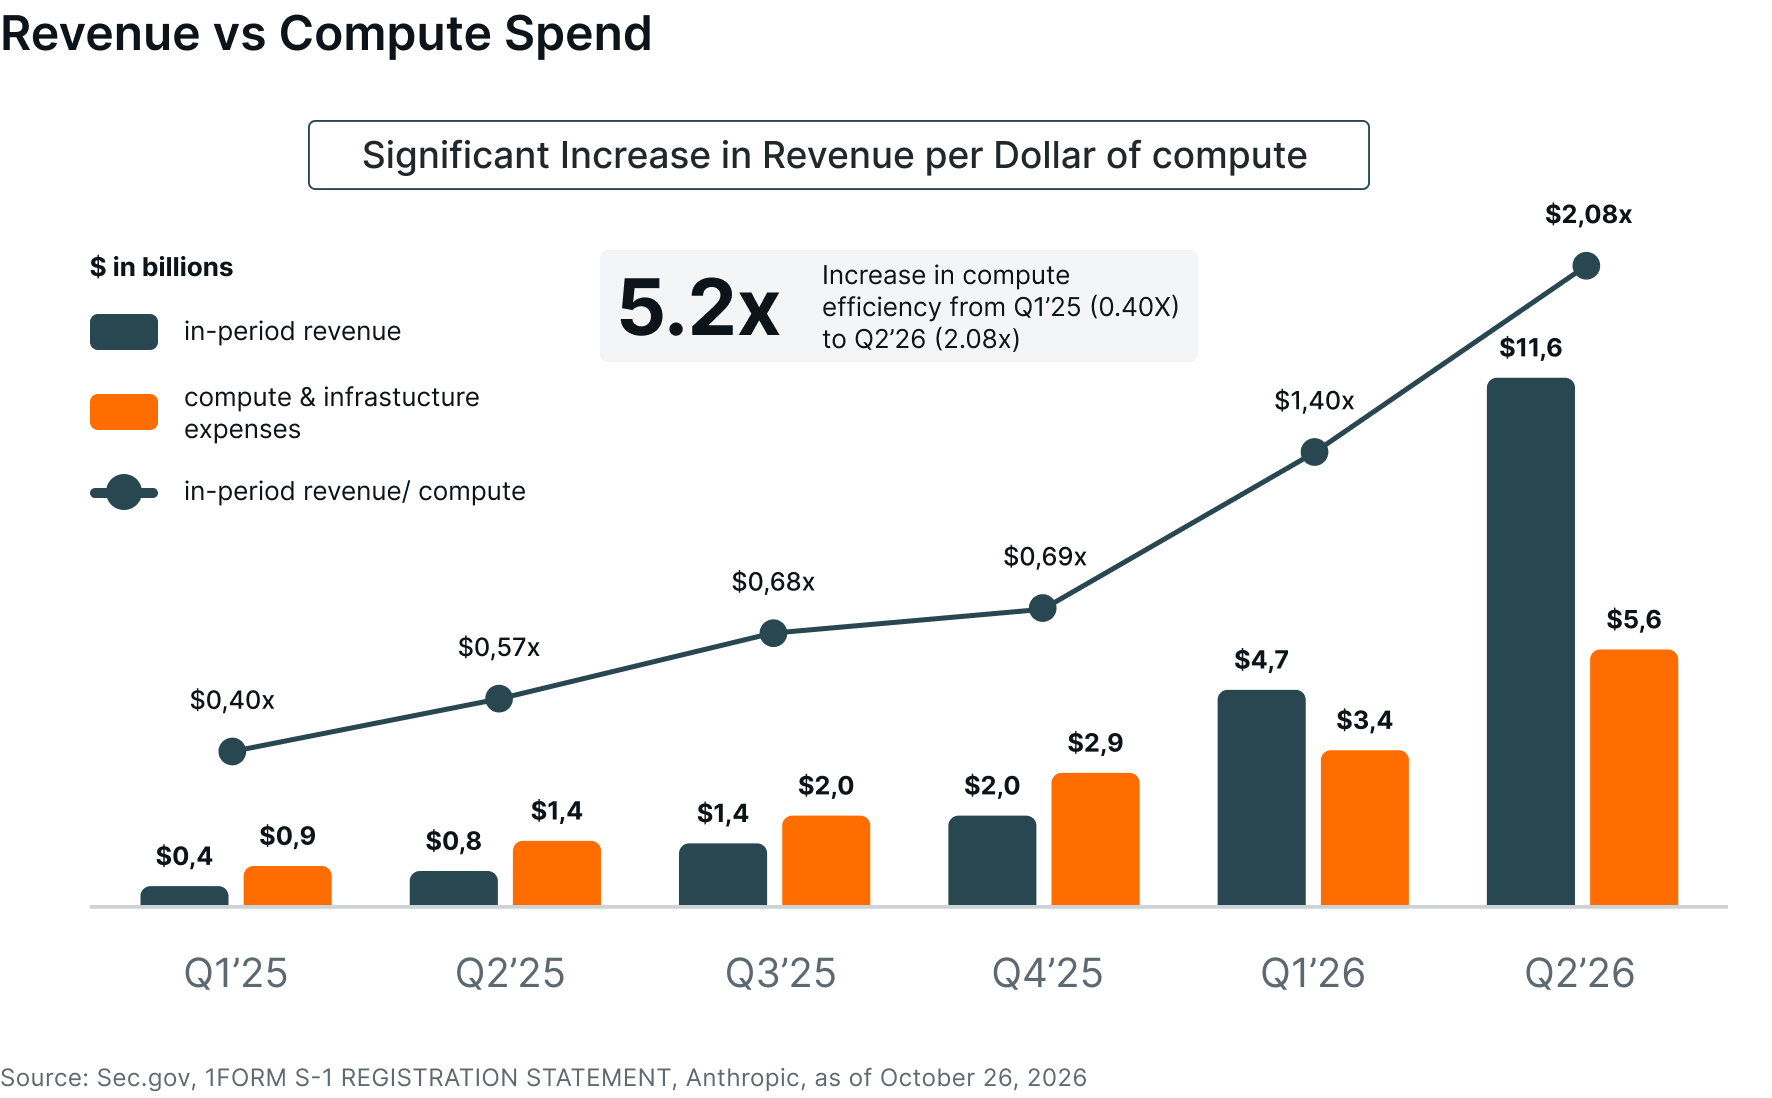
It’s worth highlighting the fact that since the start of last year, Anthropic has seen a strong positive relationship between revenue and compute spend. This is illustrated in the chart above.
Notably, the ratio of in-period revenue/compute has been trending up. This potentially justifies its high level of spending on compute – the more it has spent the more revenue it has been able to generate.
The Bull Case Versus the Bear Case
In summary, the S-1 filing contained ammunition for both the bulls and the bears. While the filing showed that revenue is soaring, it also showed large losses and rising compute spending.
If there’s one takeaway here it’s that the stock's post-listing path is bound to be a volatile ride. At this stage, we don’t know whether Anthropic will be a public market success or failure.
Footnotes:
1Sec.gov, 1FORM S-1 REGISTRATION STATEMENT, Anthropic, as of October 26, 2026
2LSEG, as of November 3, 2026
3Yahoo Finance, Anthropic's new IPO filing puts its computing bill near $900 billion, as of November 2, 2026