Your capital is at risk if you invest. You could lose all your investment. Please see the full risk warning here.
Semiconductor designer NVIDIA emerged as an artificial intelligence (AI) titan in 2023, capturing investors' imaginations with its ground-breaking advancements. NVIDIA underwent a massive transformation in 2023 based on unprecedented demand for its graphic processing units (GPUs).
The company’s share price has soared to remarkable heights, propelled by its leadership in the artificial intelligence (AI) chip market. Although the AI mania has subsided over the past two months and shares of NVIDIA have declined 18%, its share price has nearly tripled so far in 2023, keeping it as the S&P 500 best-performing stock this year.
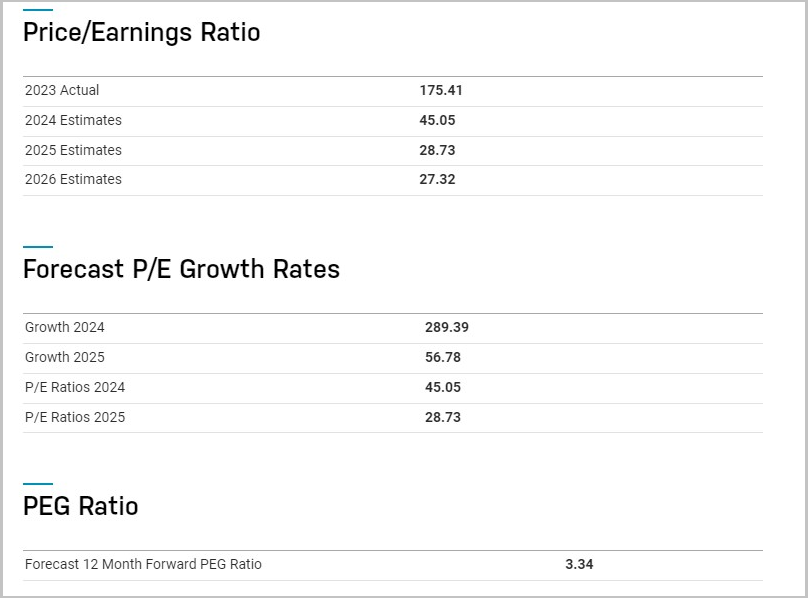
However, after a turbo charged run in the share price the debate among investors around NVIDIA's valuation intensifies. The company’s valuation has reached incredibly stretched levels with huge expectations priced in. The company reports on the 21 st of November and investors are eagerly awaiting Q3 results.
In Q2 revenue skyrocketed 101% year over year to $13.51 billion. The company projects this trend to continue into Q3, giving guidance for $16 billion in revenue. Therefore, earnings and forward guidance will be scrutinised, as the company must continue to substantially grow its revenue over the next year to justify its current valuation.
Source: Nasdaq
The company shares tumbled 9% last week after U.S. government officials announced more stringent curbs on exports of advanced AI chips to China, dragging down the company share price. Other chipmakers with AI exposure such as Broadcom, AMD, and Intel also traded lower in response to the news.
In a regulatory filing, NVIDIA highlighted the possibility of export controls affecting its ability to complete product development in a timely manner. The company also said that these controls could potentially disrupt support for existing customers of affected products and their supply to regions impacted by these restrictions.
Given NVIDIA’s lofty valuation the company must continue to execute. While it won’t be easy to continue to grow revenue at current rates for long, given the huge competition coming in, it won’t be impossible either. While the secular AI growth is in its early stage and the long-term outlook for the company remains positive, we expect some volatility in the near-term.
Proactive investors seeking to capture the short-term swings of NVIDIA’s share price and looking to gain magnified exposure may consider our +3x Long NVIDIA ETP.
Your capital is at risk if you invest. You could lose all your investment. Please see the full risk warning here.
 Market Insights