Your capital is at risk if you invest. You could lose all your investment. Please see the full risk warning here.
Bank Earnings Season Sends a Clear Signal to Markets
U.S. banks entered the fourth-quarter earnings season with expectations running high, and for the most part, they delivered. Trading desks thrived, capital positions remained robust, and shareholder returns accelerated. Yet despite headline earnings beats across much of the sector, the market reaction was notably restrained. The reason is simple: investors are increasingly focused on the durability of earnings rather than their absolute level.
Q4 results revealed a banking sector that is profitable and well-capitalised, but also one going through uneven revenue growth, rising costs, and a macro backdrop that remains supportive for now.
Trading Desks Lead the Charge
The standout theme across the sector was the strength of trading and markets businesses. Elevated volatility, geopolitical uncertainty, and active client repositioning throughout 2025 created fertile conditions for banks’ equities and fixed-income desks.
Goldman Sachs posted record trading revenue, while JPMorgan reported a 17% year-on-year jump in markets revenue, with both fixed income and equities outperforming expectations. Morgan Stanley also benefited from strong equity trading, reinforcing the idea that market activity, not lending growth, has been the primary earnings engine for large banks.
This strength helped cushion softer areas elsewhere and highlights how sensitive bank earnings remain to market conditions.
Investment Banking Recovery Remains Uneven
While deal activity improved compared to earlier in the cycle, the recovery in investment banking was far from uniform.
Morgan Stanley emerged as the clear winner, with investment banking revenues surging nearly 50% year on year, exposing the upside leverage banks can achieve when M&A and capital markets reopen. By contrast, JPMorgan reported a modest decline in investment banking fees, while Goldman’s strong advisory and underwriting performance was overshadowed by losses in other divisions.
The takeaway is that investment banking momentum is real, but selective. Corporates are engaging, but not indiscriminately, and fee recovery remains highly dependent on sector, geography, and transaction size.
Goldman's Results Highlight Earnings Quality Concerns
Goldman Sachs’ quarter encapsulated the broader earnings paradox facing banks. On the surface, results were strong: earnings comfortably beat expectations, capital ratios were healthy, and shareholder returns were robust. Beneath that, however, revenue missed forecasts, operating expenses rose, and losses tied to the exit from the Apple Card program weighed on results.
The markdowns associated with transferring Apple Card loans and terminating the partnership were a reminder that strategic missteps in consumer finance can be costly. While management remains confident in accelerating momentum into 2026, investors appear more cautious, focusing on revenue consistency and cost discipline rather than long-term ambition.
Wealth Management Provides Stability
In contrast to more cyclical businesses, wealth and asset management continued to offer a stabilising force. Morgan Stanley’s wealth franchise once again proved its value, with strong net new asset inflows and rising client assets supporting steady revenue growth. Goldman’s assets under supervision reached a record high, extending a multi-year trend of fee-based inflows.
This highlights an important structural shift across investment banks: diversified income streams, particularly wealth management, are increasingly critical to smoothing earnings volatility across cycles.
Capital Returns Remain a Key Support
Capital strength across the sector remains unquestionable. CET1 ratios were comfortably above regulatory requirements, allowing banks to continue returning capital aggressively. Goldman, JPMorgan, and Citigroup all reaffirmed their commitment to dividends and buybacks, reinforcing banks’ appeal to income-focused investors.
However, capital returns alone were not enough to drive shares higher, suggesting that much of this positivity is already priced in.
Why Markets Reacted Cautiously
Despite broadly solid earnings, bank stocks struggled to gain traction following their earnings results. The explanation lies in expectations. After a strong run into earnings season, markets were primed for confirmation that revenue growth would accelerate meaningfully into 2026. Instead, results pointed to earnings that remain heavily reliant on trading strength, alongside rising expenses and lingering structural challenges.
Management commentary also struck a cautious tone. While CEOs highlighted economic resilience, they were equally clear about risks tied to geopolitics, inflation persistence, regulatory uncertainty, and concerns around central bank independence. This tempered optimism and encouraged profit-taking.
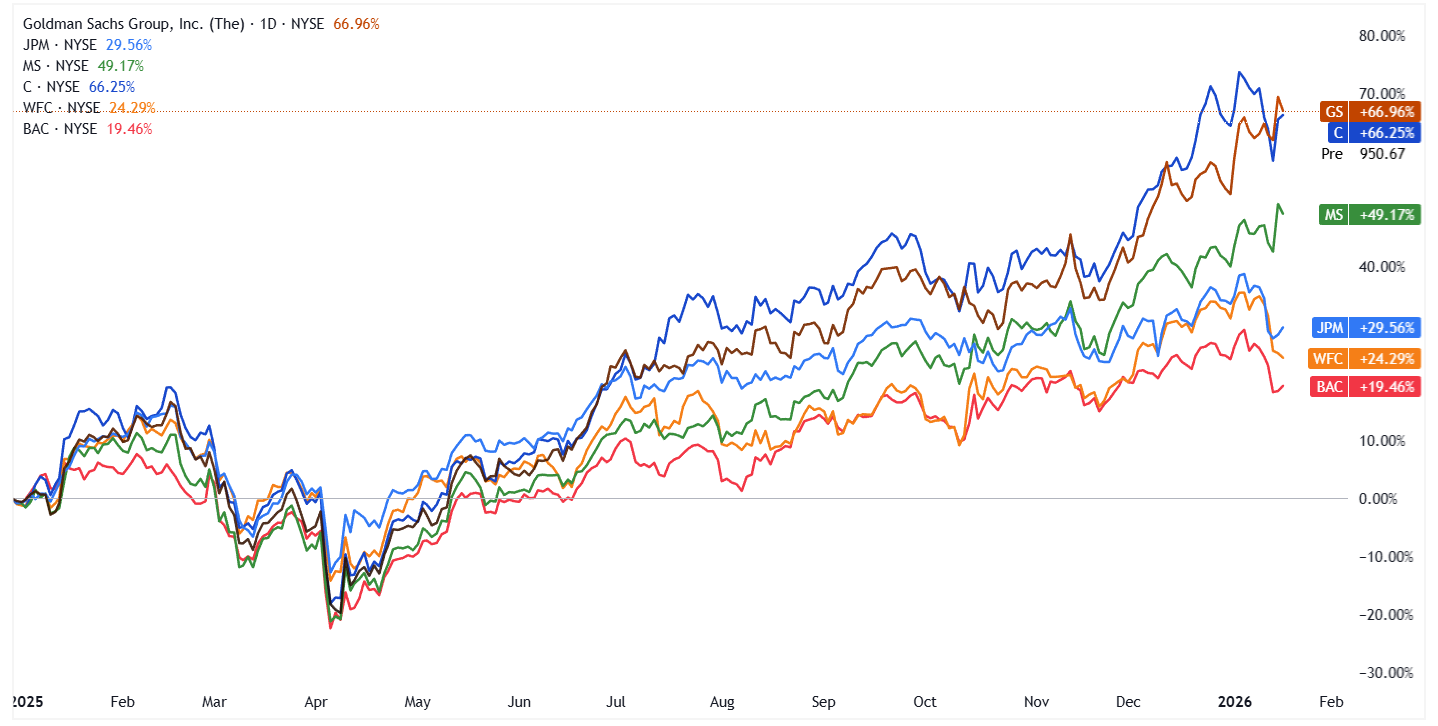
Source: TradingView. Daily price chart of the big 6 US banks as of 20 January 2026.
What Bank Earnings Say About the Broader Market
For the broader market, Q4 bank earnings send a nuanced signal. Financial conditions remain supportive, liquidity is flowing, and risk appetite has not disappeared. At the same time, earnings growth is becoming more selective and increasingly dependent on favourable market conditions rather than organic credit expansion.
This suggests a market environment that is still rewarding, but one that may struggle if growth slows or financial conditions tighten unexpectedly. Banks are telling us that the system is healthy, but not immune.
Bottom Line
Q4 bank earnings confirmed that US financial institutions are profitable, resilient, and well-positioned heading into 2026. Trading strength, solid capital buffers, and shareholder returns provide a strong foundation. However, uneven revenue growth, rising costs, and cautious forward guidance explain why markets responded with restraint rather than enthusiasm.
For investors, the message is clear: banks are not signalling stress, but they are no longer offering easy upside. From here, performance will hinge less on balance sheet strength and more on the direction of markets, policy, and economic momentum in the year ahead.
Your capital is at risk if you invest. You could lose all your investment. Please see the full risk warning here.
 Market Insights