

Your capital is at risk if you invest. You could lose all your investment. Please see the full risk warning here.
Tesla posted record third-quarter revenue as buyers rushed ahead of the tax credit expiry in September. Despite a 12% rise in sales, Tesla’s profits declined sharply, pressured by higher tariffs, increased research and development (R&D) costs, and fading regulatory credit income, following recent policy changes under the Trump administration.
Tesla Sales Soar but Profits Sink
Tesla reported $28.1 billion in revenue for the third quarter, exceeding Wall Street’s estimate of $26.4 billion. This marks a return to top-line growth after two consecutive quarters of declines, highlighting strong demand in the run-up to the expiration of U.S. federal EV tax credits.
However, earnings came in light at $0.50 per share (non-GAAP), below consensus estimates of $0.55. Net income plunged 37% year-over-year to $1.37 billion, reflecting lower EV prices and rising operating costs.
While record deliveries of 497,099 vehicles fuelled headline revenue, Tesla’s operating income fell 40% compared to last year, weighed by shrinking gross margins (18% vs. 19.8% YoY) and higher R&D spending tied to AI and automation projects.
Automotive regulatory credit revenue dropped to $417 million in the quarter, down from $739 million a year earlier and $435 million in the previous quarter, eroding one of Tesla’s once-reliable profit source. 1
Tesla’s Record Deliveries Driven by Expiring Tax Credit
The quarter’s record deliveries were largely driven by a temporary demand surge in the U.S., as consumers rushed to purchase electric vehicles before the federal EV tax credit expired under the Trump administration’s spending bill.
This one-off catalyst helped Tesla post its best-ever quarterly deliveries, but demand could soften in the coming quarters. With Europe facing a sales slowdown, exacerbated by increased competition and public backlash against Musk’s political rhetoric, maintaining volume growth could be a challenge.
Tesla’s Price Cuts Hit Margins Amid Rising Costs
Tesla’s aggressive price cuts aimed at boosting sales have eroded profitability and the company’s automotive gross margin continues to slide.
Tesla reported a broad rise in expenses, with operating costs up 50% year-over-year, driven by AI and R&D investments, higher stock-based compensation, and increased per-vehicle costs linked to tariffs.
Energy Business Emerges as a Growth Engine
While the automotive segment remains Tesla’s backbone, its energy generation and storage business stood out this quarter. The division recorded 44% revenue growth to $3.42 billion, driven by the success of Megapack energy systems and large-scale deployments for datacentres, including sales to Musk’s AI startup, xAI.
Energy now accounts for around one-quarter of total revenue, signalling Tesla’s gradual transformation into a multi-segment tech-energy company rather than a pure EV play.
Source: Leverage Shares. Holdings of +3x Long Artificial Intelligence ETP.
Technical Analysis
CEO Elon Musk offered few specifics about production targets, instead emphasizing on long-term visions. While investors were looking for near-term visibility, Tesla provided cautious commentary and limited forward guidance.
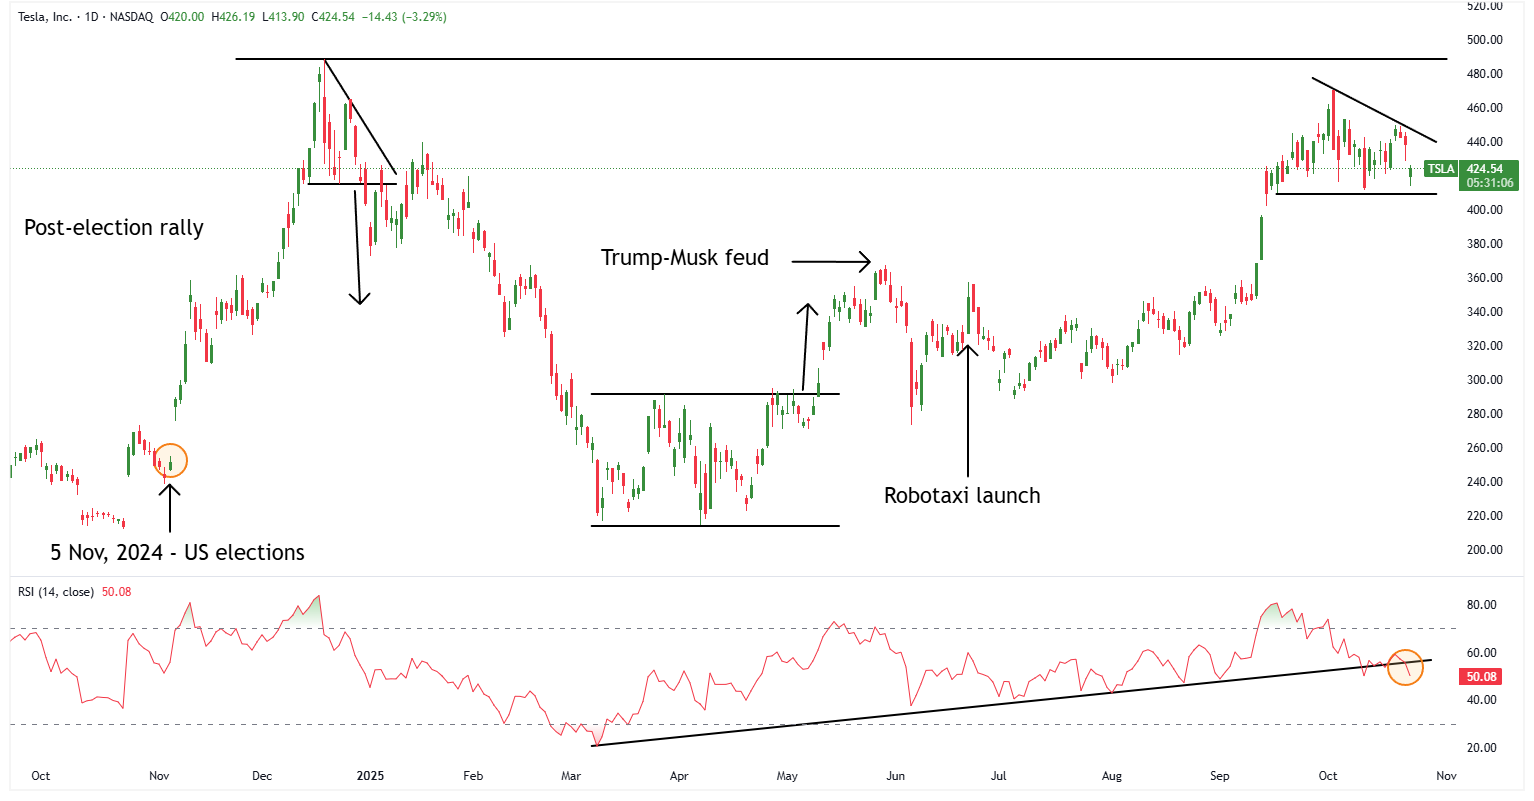
Tesla has staged an impressive recovery from its April lows, approaching its all-time high of $488.54, which could act as near-term resistance. The stock is up 4% year-on-year, underperforming the broader market and other mega-cap peers, reflecting ongoing investor scepticism about the company’s short-term prospects.
Following the report, Tesla shares dropped as investors focused on margin compression and a lack of clear forward guidance. While there are no immediate signs that the rally from April is reversing, the recent deterioration in the Relative Strength Index (RSI) suggests a potential short-term pullback. A decisive drop below the minor support level of $411.45 would confirm a reversal and could trigger a decline toward $365.00.
Key Takeaways:
Short-term volatility likely to persist: While Tesla delivered record revenue, the earnings miss, and soft margin outlook suggest continued share price pressure in the near term. Investors are likely to react to a weaker profitability and limited guidance.
Energy division is promising: The strong performance in the energy segment highlights a long-term growth driver that could help offset margin pressures from automotive pricing strategies.
Margins remain the central risk: With vehicle prices down and costs rising, Tesla’s profitability will depend on operational discipline and the pace of adoption for higher-margin software and energy solutions.
Investor patience will be tested: Musk’s focus on AI, robotics, and autonomous vehicles is a strategic bet, but tangible financial benefits may still be several quarters away.
Stock reaction: After an early 2025 rebound, the Q3 results may cap further upside in the short term. Long-term investors could view any pullback as an opportunity, but near-term sentiment remains cautious.
Professional investors looking for magnified exposure to Tesla may consider Leverage Shares +3x Long Tesla or -3x Short Tesla ETPs.
Footnotes:
Tesla Investor Relations: chrome-extension://efaidnbmnnnibpcajpcglclefindmkaj/https://assets-ir.tesla.com/tesla-contents/IR/TSLA-Q3-2025-Update.pdf
Your capital is at risk if you invest. You could lose all your investment. Please see the full risk warning here.
 Market Insights
 Education