Your capital is at risk if you invest. You could lose all your investment. Please see the full risk warning here.
Apple Delivers a Blockbuster Quarter on iPhone Sales
Apple’s fiscal first-quarter 2026 results delivered a clear message to markets: when iPhone demand accelerates, few global companies can match Apple’s financial firepower. The company comfortably beat Wall Street expectations on both revenue and earnings, driven by record-breaking iPhone sales and a sharp rebound in Greater China, while reaffirming its ability to generate massive cash flows even amid supply constraints and rising component costs.
Apple reported revenue of $143.76 billion, up 16% year-on-year, well ahead of consensus expectations of $138.48 billion. Earnings per share came in at $2.84, comfortably beating the $2.67 forecast and up from $2.40 a year earlier. Net income rose to $42.1 billion, highlighting Apple’s continued operating leverage at scale. 1
iPhone 17: The Engine Behind the Surge
The standout feature of the quarter was iPhone performance. iPhone revenue surged 23% year-on-year to a record $85.27 billion, smashing expectations of $78.65 billion. CEO Tim Cook described demand as “simply staggering” a notable reversal from the prior year’s holiday quarter, when iPhone sales had declined slightly. 2
The results represent the first full quarter of availability for the iPhone 17 lineup, launched in September, which appears to have reignited both upgrade demand and brand switching. Cook highlighted record upgrade rates and double-digit growth in switchers, suggesting Apple is not only retaining its installed base but actively pulling users from rival ecosystems.
China Roars Back into Growth
Perhaps the most strategically important development was Apple’s resurgence in Greater China. Sales across mainland China, Taiwan, and Hong Kong jumped 38% year-on-year to $25.53 billion, far exceeding expectations and marking a decisive turnaround after multiple quarters of weakness. 2
The strength was overwhelmingly product-driven, with iPhone sales leading the charge. Apple set an all-time record for iPhone upgraders in mainland China, alongside strong growth from first-time Apple customers, which is an encouraging signal in a market where domestic competitors have intensified pressure.
Installed Base Hits 2.5 Billion Devices
Apple’s expanding ecosystem remains a core pillar of its long-term strategy. The company now boasts an active installed base of over 2.5 billion devices, up from 2.35 billion a year earlier. This growing footprint underpins Apple’s Services business and reinforces the durability of recurring revenue streams across software, subscriptions, and warranties.
Services: Solid but Not Spectacular
Apple’s Services revenue reached approximately $30 billion, growing 14% year-on-year and broadly in line with expectations. While not a surprise beat, the performance underscores the segment’s consistency and profitability. Apple TV+ viewership rose 36% in December, reflecting growing engagement across Apple’s content platforms. 2
Management guided for Services growth to remain at a similar rate in the current quarter, suggesting stability even as competition in streaming and digital services intensifies.
Mixed Hardware Performance Beyond iPhone
Performance across Apple’s non-iPhone hardware was more uneven:
Mac revenue declined 7% year-on-year to $8.39 billion, missing expectations despite the November launch of updated MacBook Pro models featuring the new M4 chip.
iPad revenue rose 6% to $8.6 billion, beating estimates, with half of the buyers new to the iPad, which is a promising sign for category expansion.
Wearables, Home and Accessories revenue fell 2% to $11.49 billion, missing expectations, reflecting softer demand across Apple Watch, AirPods, and Vision Pro. 2
Margins Hold Firm
Apple reported a gross margin of 48.2%, exceeding estimates and landing at the high end of its historical range. However, management struck a cautious tone on margins looking ahead. The ongoing global memory shortage, driven by massive AI data centre buildouts, is pushing component prices higher.
Cook acknowledged that memory pricing had only a minimal impact in Q1 but warned that pressures are likely to intensify in the current quarter, acknowledging a more challenging cost environment.
AI Strategy: Partnerships Over Spending Sprees
While peers like Microsoft and Meta are committing hundreds of billions to AI infrastructure, Apple is pursuing a more measured approach. The company recently announced a strategic partnership with Google, integrating Gemini AI models to power Apple Intelligence and a more personalised Siri, expected later this year.
Apple also confirmed the acquisition of Israeli startup Q.ai, specialising in facial micro-expression analysis, highlighting Apple’s willingness to pursue targeted AI acquisitions rather than large-scale capital deployments. Research and development spending rose sharply to $10.89 billion, reinforcing Apple’s commitment to AI without matching the spending intensity of rivals.
Supply Constraints and Outlook
Despite the strong demand environment, Apple remains in what Cook described as “supply chase mode.” Constraints around advanced chip manufacturing and rising memory prices are limiting Apple’s ability to fully meet demand, particularly for iPhones.
For the current quarter, Apple guided for revenue growth of 13%–16% year-on-year, implying revenue of up to $110.66 billion, well above current analyst expectations. The company also returned nearly $32 billion to shareholders during the quarter through dividends and share repurchases, underlining its unmatched capital return profile.
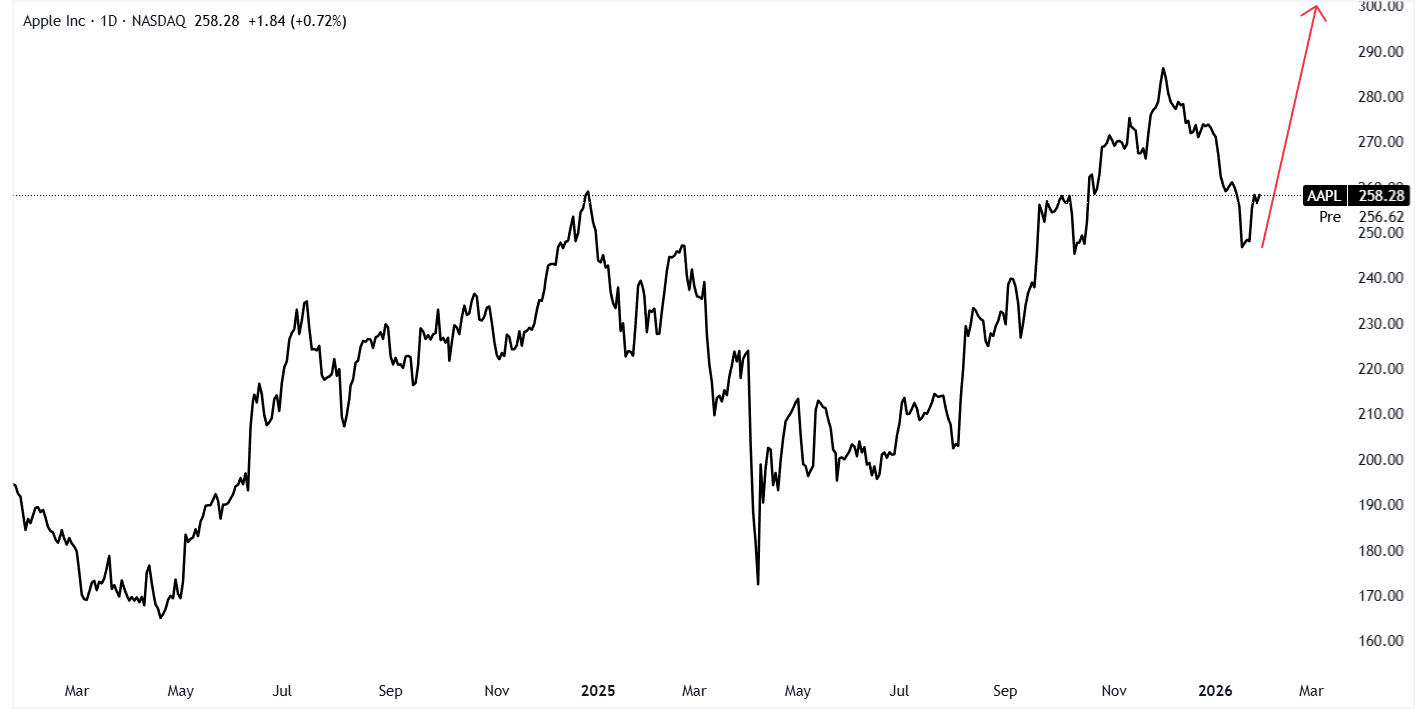
Source: TradingView. Apple daily price chart as of 29 January 2026.
Conclusion:
Apple’s Q1 2026 earnings reaffirm a familiar fact: while AI leadership ebb and flow, Apple’s core strength remains its products, ecosystem, and global scale. The iPhone 17 cycle has exceeded expectations, China has re-emerged as a growth engine, and margins remain resilient despite mounting cost pressures.
However, challenges remain, particularly around AI execution and supply constraints, but for now, Apple has reminded the market that few companies can deliver growth, profitability, and shareholder returns at this magnitude when demand aligns.
Following Apple’s impressive Q1 2026 results, we see meaningful upside potential over the next 12 months and have raised our long-term price target to $300.
Professional investors looking for magnified exposure to Apple may consider Leverage Shares +3x Long Apple ETP or -3x Short Apple
Footnotes:
Apple Newsroom: https://www.apple.com/newsroom/2026/01/apple-reports-first-quarter-results/
Apple Newsroom: chrome-extension://efaidnbmnnnibpcajpcglclefindmkaj/https://www.apple.com/newsroom/pdfs/fy2026-q1/FY26_Q1_Consolidated_Financial_Statements.pdf
Your capital is at risk if you invest. You could lose all your investment. Please see the full risk warning here.
 Market Insights