Your capital is at risk if you invest. You could lose all your investment. Please see the full risk warning here.
- Treasury yields decline after Fed not as hawkish as feared
- Fed will slow the pace of its balance sheet runoff
During their April meeting last week Fed officials last decided to leave interest rates unchanged in the range of 5.25% to 5.5% as widely anticipated. The markets were relieved when Fed Chair Jerome Powel dismissed the possibility of rate hikes and announced it will shrink its balance sheet at a much slower pace in order to ease pressure in money markets.
Federal Reserve keeps interest rates unchanged
The Federal Reserve's announcement to leave interest rates at their current level, as stubborn inflation continues to push back the timing of the first rate cut, leading to a sharp drop in Treasury yields.
Fed officials expressed concerns that there has been luck of further progress on inflation moderation over the past few months and that strong evidence that disinflation is sustainable is required before they start lowering interest rates.
The Fed will slow the pace of quantitative tightening
The Federal Reserve’s main tool is its key interest rate, but it also uses its balance sheet to either stimulate or slow down the economy. The central bank announced that from June it will let up to $25 billion in Treasuries to mature each month without replacing them, vs. $60 billion a month at present.
This is a significant slowdown of the pace at which the Fed reduces its balance sheet, allowing Treasuries to mature without reinvesting in them – a process known as quantitative tightening. This decision is a sign the central bank is easing its grip on the economy and is viewed as a dovish turn.
This announcement came as a surprise to the market and was the major driver that triggered a sharp decline in Treasury yields last week.
Central bank view on interest rates
Fed policymakers provided some guidance about the outlook for interest rates, with Fed Chair Jerome Powell clearly stating that it is unlikely that the central bank would hike interest rates, unless there is strong evidence that the current policy stance is not sufficiently restrictive to bring inflation to the Fed’s 2% target.
The Fed signalled that it still plans to cut interest rates at some point, but addressed that inflation remains high and the path forward in uncertain at this point.
While the decision to hold rates steady was no surprise, the significant moderation in tapering was unexpected and is a bullish development for bonds (bond prices move in the opposite direction to yields).
Following the Fed statement, traders are now pricing in two rate cuts by the end of this year, starting in September, according to the CME FedWatch tool.
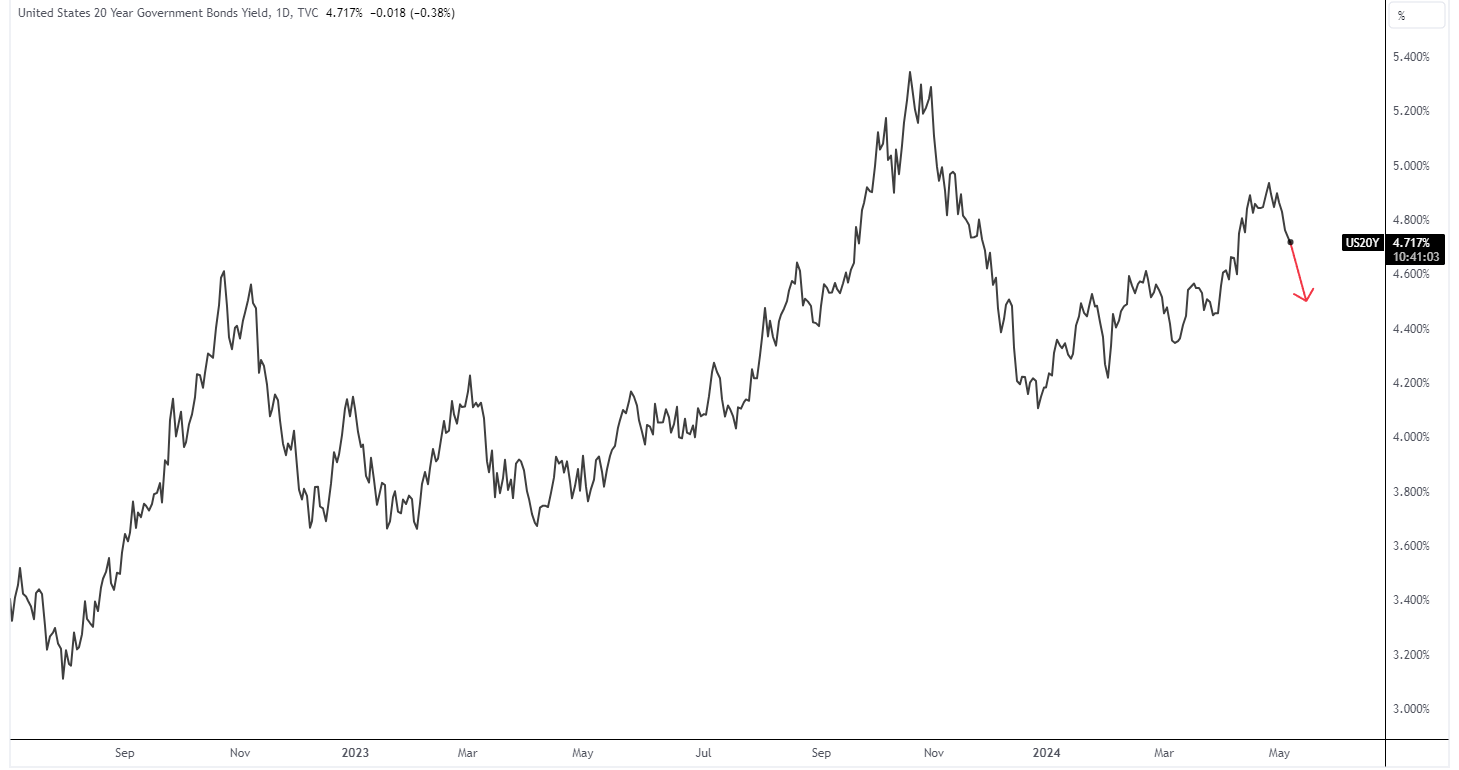
Source: TradingView
Treasury yields reaction
Following the rule out of rate hikes and the slowing pace of quantitative tightening pushed Treasury yields sharply lower. The yield of the 20-year Treasury bond declined from 4.97% on the 25 th of April to 4.70% in eight trading sessions.
The Federal Reserve appears done raising and long-term rates are likely past their picks for this cycle. While the monetary policy pivot moment is uncertain, it is surely coming. Yields this high appear attractive for bond bulls and current levels are seen as a good entry point.
Professional traders looking for magnified exposure to long dated bonds may consider Leverage Shares + 5x 20+ Year Treasury Bond or -5x Short 20+ Year Treasury Bond ETPs.
Your capital is at risk if you invest. You could lose all your investment. Please see the full risk warning here.
 Market Insights
 Education